Sunday, 20 September 2026
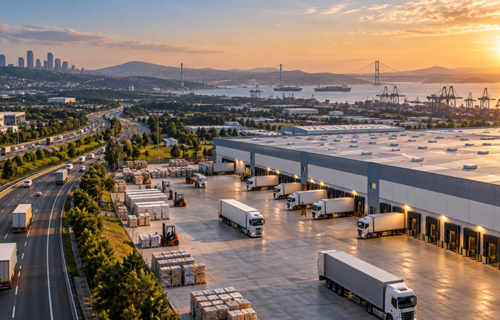
The Istanbul-Kocaeli logistics property market is facing a shortage that cannot be measured simply by counting warehouse floor space. Demand for modern facilities remains strong, while the supply of suitable high-quality properties is limited. Requirements are particularly concentrated on facilities below 10,000 sqm and large units above 25,000 sqm, indicating a mismatch between existing inventory and the buildings companies currently need.
The imbalance is particularly visible across Istanbul’s European and Asian logistics markets and neighbouring Kocaeli, which together form Türkiye’s principal industrial and distribution corridor. Vacancy is below 2% in parts of the market, while prime logistics rents reached approximately USD 10.50 per sqm per month during the second quarter of 2026. Limited availability of good-quality buildings that can be occupied relatively quickly is helping maintain competition for the best properties.
Location is an important part of the equation. Istanbul provides access to Türkiye’s largest concentration of consumers and businesses, while Kocaeli combines manufacturing clusters with motorway, port and industrial infrastructure. These advantages generate demand from logistics operators, manufacturers, retailers and distributors while increasing competition for development land in locations offering efficient connections to major transport routes and population centres.
The definition of a suitable warehouse is also becoming more demanding. Depending on their operations, occupiers may require greater clear heights, appropriate floor-loading capacity, efficient loading areas, sufficient yards, vehicle circulation and modern building systems. Consequently, a property can technically be recorded as available warehouse space while failing to provide the configuration required by a particular logistics or manufacturing operation.
New construction should gradually increase choice. Specialist market research identifies a total development pipeline of around 856,000 sqm across Istanbul and Kocaeli, although the amount already under construction is lower and definitions of pipeline supply vary between market reports. Projects are also at different development stages, while some space may be designed for specific occupiers or committed before completion. The headline pipeline therefore cannot be treated as an equivalent amount of future vacant supply.
Delivering additional modern stock also presents challenges. High land values, rising construction costs and limited availability of appropriately located sites can complicate new development, particularly where projects require increasingly sophisticated specifications. These constraints can make speculative schemes harder to justify even when vacancy is low and rents for prime properties are relatively strong.
The result is a market where the central issue is increasingly the quality, configuration and location of available space rather than the absolute quantity of warehouses. The second half of 2026 will provide an important test of whether new development can reduce the mismatch between existing stock and occupier requirements. Until sufficient modern and well-connected facilities reach the market, competition for the best logistics properties across Istanbul and Kocaeli is likely to remain strong.
Source: CIJ.World Research & Analysis Team