Tuesday, 27 October 2026
Microsoft is preparing to offer voluntary severance packages to approximately 60,000 eligible employees as the technology group seeks to manage operating expenditure while directing substantial investment towards artificial intelligence and digital infrastructure. The programme, reported on 26 October 2026, covers selected divisions in the United States, Canada, India and the United Kingdom. Although the initiative could result in workforce reductions, the company has not disclosed how many employees it expects to accept the offer, making the eventual impact on staffing levels uncertain.
The voluntary departure programme reportedly applies to employees at vice-president level and below across several business divisions, including artificial intelligence, finance, human resources, gaming and software development. Certain operational teams, including employees responsible for parts of Microsoft’s data centre infrastructure, are excluded. The company employed approximately 223,000 full-time staff worldwide at the end of June 2026, including around 121,000 in the United States. The employees eligible for the programme therefore represent approximately 27% of its global workforce, although eligibility does not mean that these positions will necessarily be eliminated.
The restructuring follows an earlier voluntary departure initiative introduced in April 2026, when approximately 8,750 employees in the United States were reportedly offered severance arrangements. Microsoft’s latest programme suggests that the company is continuing to review its organisational structure as automation and artificial intelligence change the requirements of individual business functions. The measures also reflect the financial pressures facing major technology companies as they seek to balance expenditure on personnel with increasingly expensive computing infrastructure.
At the same time, Microsoft is directing considerable financial resources towards expanding its technological capacity. According to the reported figures, the company expects capital expenditure of approximately $50 billion during the first quarter of its 2027 financial year, while investment for calendar 2026 could reach $175 billion. A substantial proportion of this expenditure is associated with artificial intelligence infrastructure, including data centres, computing equipment and supporting systems. The scale of the investment illustrates the changing allocation of capital within the technology sector, where physical infrastructure is becoming increasingly important to the delivery of digital services.
For Europe’s commercial property market, changes in technology-sector employment could influence demand for corporate office accommodation, particularly in cities with substantial concentrations of international technology companies. London, Dublin, Amsterdam and other established European technology centres have attracted major occupiers seeking access to skilled employees and international business networks. Any sustained reduction in administrative or corporate staffing could encourage companies to reassess their office requirements, although the geographical distribution of Microsoft’s proposed departures has not been disclosed and no changes to its European property portfolio have been announced.
The wider implications for office investors extend beyond the immediate restructuring. Technology companies have traditionally been important occupiers of modern office buildings, frequently requiring flexible accommodation capable of supporting collaborative work and specialist technical functions. As artificial intelligence becomes more widely integrated into business operations, changes in staffing requirements could alter how these companies use their premises. For landlords, the principal concern will be whether reduced employee numbers translate into lower space requirements, changes to workplace configurations or different expectations when existing leases approach renewal.
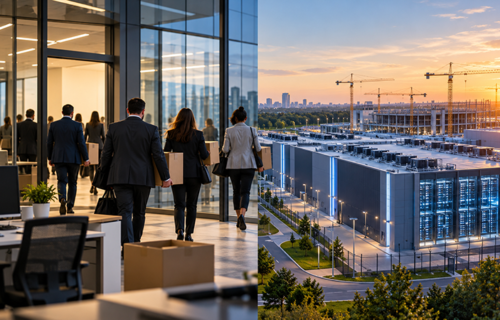
In contrast, demand for data centre infrastructure could continue expanding as technology companies increase spending on computing capacity. Microsoft’s investment programme reflects the substantial physical requirements of artificial intelligence, including facilities capable of accommodating high-density servers, advanced cooling equipment and reliable electricity supplies. For European developers and infrastructure investors, these requirements create opportunities in specialised industrial property, although suitable development locations remain constrained by electricity availability, planning procedures and the cost of connecting new facilities to power networks.
The growth of data centre investment also creates different employment and property requirements from those associated with conventional corporate offices. Construction projects generate demand for contractors, engineers and specialist installation companies, while completed facilities require technical personnel responsible for maintenance, security and operational reliability. However, data centres generally accommodate considerably fewer permanent employees per square metre than traditional office buildings. Consequently, investment in digital infrastructure should not be interpreted as a direct replacement for employment or occupied floor space potentially lost through corporate restructuring.
The changing relationship between technology employment and infrastructure expenditure could become increasingly relevant to European real estate investment strategies. Institutional investors and developers are already assessing the long-term prospects of conventional offices alongside opportunities in digital infrastructure and energy-related property assets. Microsoft’s reported restructuring provides another example of how technology companies may simultaneously reduce expenditure in some business functions while committing substantial capital to facilities supporting future growth. Nevertheless, the implications for individual European property markets will depend on the location of workforce changes, future leasing decisions and the geographical distribution of infrastructure investment.
For the European property sector, the central issue is not simply the potential reduction in Microsoft’s workforce but the broader redistribution of investment between people, workplaces and computing infrastructure. While corporate restructuring may introduce additional uncertainty for office landlords, expanding artificial intelligence capacity could support demand for data centres, electricity infrastructure and specialist construction. The extent of these changes remains uncertain, but the company’s reported plans illustrate how investment priorities within the technology industry could influence European commercial property demand over the coming years.
Source: CTK