Tuesday, 29 September 2026
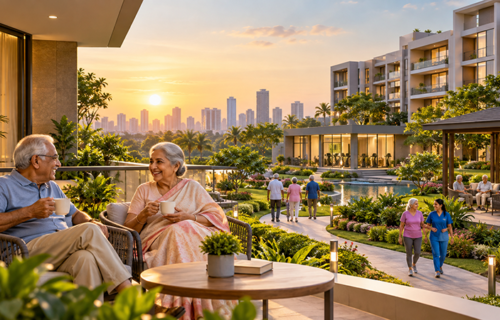
India’s demographic story is beginning to change. While the country remains associated with a young workforce, its population aged 60 and above is expanding rapidly, creating a potentially significant new market for real estate investors and operators. India currently has an estimated 166-170 million seniors, with the number projected to reach around 230 million by 2036 and more than 340 million by 2050. This demographic shift is bringing senior housing, assisted living and healthcare-linked accommodation onto the institutional property agenda.
Organised supply remains extremely limited. India had only around 25,000 professionally developed senior-living units by mid-2026, representing roughly 1-1.5% of the estimated addressable market. The imbalance between existing stock and the country’s growing senior population creates considerable room for expansion, particularly as the market moves beyond traditional retirement housing towards professionally operated communities.
Demand is also being reinforced by structural changes within Indian households. Smaller families, migration to major employment centres and children living overseas are changing how older Indians approach retirement. For a growing segment of middle- and higher-income households, senior communities can offer an alternative combining independent accommodation with security, social facilities, maintenance and access to healthcare and other support services.
Institutional capital is beginning to respond. The establishment in 2026 of a ₹20 billion investment platform involving Primus Senior Living and HDFC Capital demonstrated the potential for senior housing to move beyond individual developments towards larger professionally managed portfolios. Industry forecasts also point to substantial expansion over the remainder of the decade, although the market remains small compared with India’s established office, logistics and residential sectors.
The economics differ significantly from conventional residential property. Well-managed senior communities can achieve occupancy of around 80–85%, providing the potential for recurring revenues, but operators also carry significant service responsibilities. Healthcare coordination, food, housekeeping, security, recreation and staffing mean that performance depends as much on operating expertise as on property ownership. Establishing scalable and repeatable operating models will therefore be central to attracting larger pools of institutional capital.
The opportunity also extends beyond independent senior housing. As India’s population ages further, demand is expected to expand across assisted living, rehabilitation, physiotherapy, diagnostics, home healthcare and professional caregiving. Most organised supply currently targets relatively independent residents, leaving the more care-intensive end of the market comparatively undeveloped. This could create opportunities for partnerships between developers, healthcare companies, specialist operators and long-term investors.
Senior living is not yet an institutional asset class on the scale of offices or logistics, nor is there sufficient evidence to assume it will quickly become a significant REIT sector. Supply remains fragmented, business models vary and many projects continue to rely on individual unit sales rather than long-term institutional ownership. Greater portfolio scale, standardisation, regulatory clarity and a longer operating track record will be required before the sector can consistently attract mainstream real estate capital.
Nevertheless, India’s demographic trajectory makes senior living increasingly difficult for investors to ignore. With more than 340 million people potentially aged over 60 by 2050 and organised supply starting from an exceptionally low base, the investment opportunity extends beyond simply constructing retirement homes. The larger opportunity is the creation of a professionally managed ecosystem combining property, healthcare and services, potentially turning India’s ageing population into one of the country’s most significant emerging alternative real estate markets.
Source: © CIJ.World India Research & Analysis Team