Wednesday, 30 September 2026
Slovakia is heading towards a modest improvement in economic growth, supported by a stronger pipeline of publicly funded projects, although higher borrowing costs and weak private-sector momentum continue to create a challenging environment for property investment and development.
The National Bank of Slovakia expects GDP to expand by around 0.8% in 2026 before growth strengthens to 1.9% in 2027 and 2.7% in 2028. The outlook represents an improvement from the central bank’s previous expectations, but still points to relatively limited economic expansion this year.
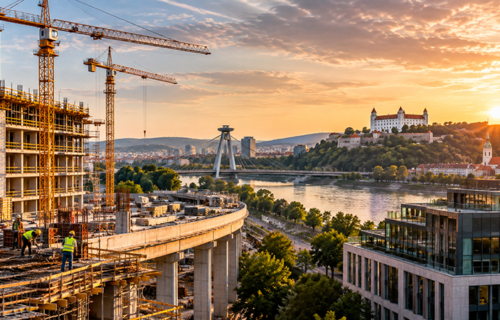
Public investment is providing an important counterweight to the slowdown. Increased deployment of European funding, together with government and municipal expenditure, is supporting capital projects at a time when other parts of the economy remain less dynamic. Earlier forecasts from both the European Commission and Slovakia’s Finance Ministry also identified investment backed by European funds as one of the main sources of economic support during 2026.
Recent economic data underline the contrast. Slovakia’s economy expanded by 0.8% year-on-year during the second quarter, according to the Statistical Office, but investment activity remained subdued. The stronger public-project pipeline could therefore become increasingly important for construction companies and suppliers during the remainder of the year and into 2027.
For the real estate industry, greater spending on transport, municipal infrastructure and other capital projects can improve development conditions in locations benefiting from new infrastructure. However, this does not necessarily translate into an immediate recovery in private commercial property development or investment transactions. Developers still have to contend with financing costs, construction economics and relatively weak economic growth.
The financing environment has also become less favourable following renewed monetary tightening in the euro area. The European Central Bank increased its key rates in September, taking the deposit facility rate to 2.50% and the main refinancing rate to 2.65%. The effect of the latest increase is expected to work gradually through corporate and property lending, potentially increasing the cost of financing new developments and acquisitions.
Slovakia’s residential market presents a further contrast with the subdued economy. Residential property prices were 9.51% higher year-on-year in the second quarter of 2026, according to NBS data. Meanwhile, the average interest rate on housing loans with fixation periods of between one and five years stood at 3.69% in July. Continued price growth combined with elevated borrowing costs is maintaining pressure on housing affordability.
Inflation is expected to average around 3.6% in 2026 before moderating next year. Public finances remain another constraint, with sizeable government deficits and rising debt limiting the room for continued domestic fiscal support. This increases the importance of efficiently deploying available European funding while the current investment cycle remains active.
For Slovakia’s property and construction markets, the resulting picture is therefore uneven rather than broadly expansionary. Public and EU-backed investment is creating opportunities around infrastructure and construction, while higher financing costs and slow economic growth encourage greater selectivity among private developers and institutional investors. The strength of the next phase of the property cycle will depend increasingly on whether infrastructure-led activity can eventually translate into stronger private investment and occupier demand.