Thursday, 17 September 2026
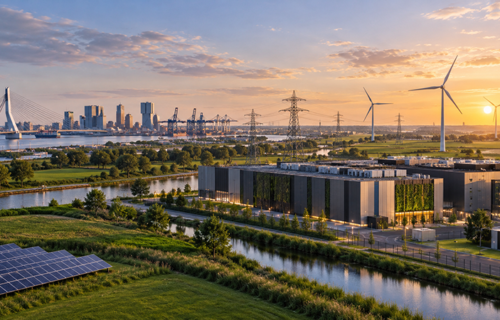
The next phase of data centre development in the Netherlands may be decided less by where technology companies want to build and more by where the electricity system allows them to build. Artificial intelligence is increasing demand for computing capacity at the same time as the Dutch power network is struggling to accommodate new connections across several regions. For property investors, this creates an unusual situation in which a site’s electricity prospects can become as important as its land, location or conventional development potential. Amsterdam remains the country’s dominant digital infrastructure market. Its international connectivity, established data centre ecosystem and concentration of technology companies give it advantages that are difficult to reproduce elsewhere. But those strengths cannot remove the physical limitations of the electricity network. Large facilities require substantial and dependable power, and securing that capacity has become one of the principal obstacles to expanding the Dutch market.
The pressure is becoming greater because the buildings required for artificial intelligence can be exceptionally electricity intensive. Large numbers of advanced processors need to operate simultaneously, creating power requirements considerably beyond those of many conventional computing facilities. Demand for AI infrastructure can therefore continue increasing even when the number of locations capable of accommodating it grows much more slowly. The result is a property market in which customer demand and development capacity can move in opposite directions. This changes how data centre land needs to be evaluated. A site may be close to Amsterdam, well connected to fibre and suitable for development, but its commercial potential is limited if sufficient electricity cannot be delivered within a realistic timeframe. Another site farther from the country’s established digital cluster could become more valuable if it offers a credible combination of electricity, fibre, planning permission and land.
There are already indications that developers are considering a wider Dutch geography. Rotterdam and northern Netherlands have attracted attention as possible locations for larger developments outside the traditional Amsterdam concentration. This does not mean that either area automatically provides an answer to the electricity problem. Both still face infrastructure, planning and network considerations. What matters is that the search for suitable capacity is encouraging developers to examine locations that previously occupied a less prominent position on the country’s data centre map. Rotterdam presents an interesting case because it combines international connectivity with one of Europe’s largest industrial and energy systems. The port region is undergoing substantial electrification as industry attempts to reduce dependence on fossil fuels. That creates extensive investment in energy infrastructure, but it also creates enormous competition for electricity. A data centre development in the region would therefore need to fit into a much broader industrial transformation rather than simply find an available development plot.
Northern Netherlands offers a different proposition. The region has significant energy infrastructure, renewable generation and greater availability of land than the country’s most densely developed urban areas. These characteristics could make individual sites attractive for digital infrastructure, but the investment case needs to be tested against actual electricity availability. Renewable generation nearby does not necessarily mean that a particular development can immediately obtain the connection it requires. Groningen consequently deserves investigation as part of the wider northern opportunity rather than being treated as a predetermined data centre hub. The same caution applies to Flevoland. Its central position and available development land appear attractive, but grid congestion demonstrates why conventional property characteristics alone are insufficient. Land can be physically suitable for a large facility while remaining commercially unusable because the electricity network cannot support it.
Eindhoven raises another possibility. The region’s semiconductor, technology, engineering and research economy creates substantial demand for advanced computing. As artificial intelligence becomes more deeply integrated into industrial research and manufacturing, access to computing infrastructure could become increasingly important to the regional economy. Yet Eindhoven illustrates the same fundamental distinction: strong demand for digital infrastructure does not guarantee that the electricity required to accommodate large facilities will be available. The Netherlands could therefore develop several different types of data centre locations rather than simply reproducing Amsterdam elsewhere. Facilities requiring extremely low latency and direct connections to existing networks may continue to cluster around established digital infrastructure. Larger computing operations with greater geographical flexibility could potentially locate farther away if power and fibre are available. Artificial intelligence may strengthen this separation because some computational workloads are less dependent on being physically close to end users than many traditional digital services.
For real estate investors, the important change is that electricity increasingly needs to be considered before the property itself. Conventional development often starts by identifying land and then arranging utilities. Large data centres can require the opposite approach. Investors may first need to understand where substantial electricity capacity can realistically become available and then identify land capable of supporting development around it. This could create substantial differences in the value of apparently similar sites. Two neighbouring parcels may have comparable access, planning characteristics and size but radically different prospects if only one can secure the required electricity connection. There is no universal Dutch price premium that can be applied to land with suitable power access, and the value of a connection depends on its size, certainty, timing and conditions. Nevertheless, the ability to deliver electricity is becoming increasingly relevant to what a data centre developer can afford to pay for land.
That could direct investors towards areas around substations, planned network reinforcement and major energy infrastructure. Instead of studying only existing data centre clusters, investors may increasingly study electricity networks and future grid investment. A site that appears peripheral on today’s digital map could become strategically important if infrastructure improvements give it access to the capacity required by tomorrow’s computing facilities. The difficulty is distinguishing between electricity that theoretically exists and electricity that can actually be delivered. The Netherlands generates substantial amounts of renewable power, but generation and usable grid capacity are not the same thing. Electricity must be transported through networks that can themselves be congested. A site near wind or solar generation is therefore not automatically a site capable of supporting a large data centre.
This makes digital property increasingly dependent on expertise traditionally associated with infrastructure investment. Due diligence may need to include detailed examination of substations, connection agreements, planned grid reinforcement and the timetable under which additional capacity could become available. Buying land on the assumption that electricity will eventually arrive could expose investors to years of delay. Data centres may also need to change the way they interact with the electricity system. Rather than operating exclusively as large, constant consumers, some facilities could potentially become more flexible participants in the network.
Battery storage is one possibility. Batteries cannot compensate indefinitely for an inadequate grid connection, but they can store electricity and help facilities manage fluctuations in demand. Computing workloads could provide another form of flexibility. Some digital services must operate continuously and respond immediately to users, but certain computational tasks can potentially be scheduled with greater freedom. Parts of AI training may therefore be capable of operating more intensively when electricity conditions are favourable and reducing demand when the network is under pressure. This would not eliminate the need for substantial power capacity, but it could make some facilities easier to integrate into constrained electricity systems.
The heat generated by computing equipment creates another opportunity. Data centres produce large quantities of thermal energy that can potentially be reused in nearby buildings or heating networks. In suitable locations, this could create a relationship between digital infrastructure and surrounding residential or commercial development. The practical challenge is that heat needs customers, distribution infrastructure and an economic structure that makes recovery worthwhile. It should therefore be considered a location-specific opportunity rather than an automatic benefit of data centre development. Where these conditions align, the future data centre could become part of a wider local energy system. Electricity would power computing, batteries could help manage consumption, some workloads could respond to network conditions and heat could potentially be supplied to surrounding users. That would make the facility more than a building containing servers. It would become a piece of energy infrastructure as well as digital infrastructure.
This has implications for the type of capital entering the sector. Data centre development already sits between property, infrastructure and technology investment. Electricity constraints could strengthen that convergence. Property developers may increasingly work alongside energy companies, infrastructure funds, specialist digital investors and utilities to secure sites and deliver the infrastructure required to operate them. Municipalities will also have greater influence over where the market develops. Electricity is needed not only for data centres but for housing, industry, electric transport and the wider transition away from fossil fuels. Local and national authorities therefore need to decide how scarce network capacity should be allocated. Projects capable of demonstrating broader economic or energy benefits may have advantages over developments viewed simply as large electricity consumers.
This competition means the Netherlands is unlikely to produce a simple replacement for Amsterdam. The more probable outcome is a broader and more specialised market in which different locations serve different computing requirements. Amsterdam can remain the country’s principal digital cluster while additional capacity emerges elsewhere when suitable combinations of electricity, fibre and land become available. Rotterdam and northern Netherlands currently provide some of the clearest evidence of this search beyond Amsterdam. Groningen, Flevoland, Eindhoven and other regions remain possibilities that need to be assessed site by site. Their future importance will depend not simply on how much land they possess or how close they are to technology companies, but on whether developers can secure the infrastructure required to turn that land into functioning digital capacity.
For investors, this creates a new way of reading the Dutch property map. The locations that appear strongest according to conventional measures may not necessarily offer the best data centre opportunities. Future value could instead emerge around electricity infrastructure that has historically received little attention from property investors. Artificial intelligence is accelerating the demand side of that equation. Grid congestion is constraining the supply side. Between them, they could create a new category of strategically valuable Dutch development land. The central question for investors is therefore no longer simply where the next data centre should be built. It is where enough electricity can realistically be secured to build it.
Source: CIJ.World Research & Analysis Team