Tuesday, 15 September 2026
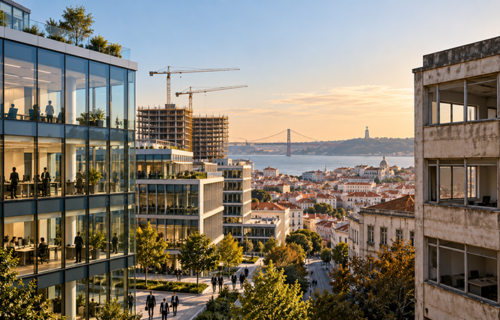
Lisbon’s office market is becoming increasingly divided between buildings capable of meeting modern corporate requirements and older properties competing for a weaker pool of demand. Leasing slowed during the first half of 2026 while new supply increased, yet rents for the strongest locations remained firm. The combination suggests that the amount of vacant space across Lisbon is becoming less important than the quality and location of the offices actually available.
Companies leased approximately 38,050 sqm during the second quarter, taking first-half activity to around 66,900 sqm. Although Q2 improved by roughly one-third compared with the opening quarter, activity remained about 44% below the same period of 2025. Across the first six months, leasing was approximately 20% lower year-on-year, pointing to a more cautious occupier market despite the improvement between Q1 and Q2.
Measuring how much office space is actually vacant is less straightforward. CBRE calculated a vacancy rate of 8.39% at the end of Q2, while Cushman & Wakefield arrived at approximately 6.6%. The difference reflects variations in the geographical boundaries, building samples and methodologies used to monitor Lisbon. More important for the market is the type of accommodation sitting behind those figures. Companies seeking recently developed or comprehensively modernised offices have very different requirements from occupiers prepared to consider older space. Energy efficiency, technical standards, workplace amenities, transport connections and flexible floorplates are increasingly influencing relocation decisions alongside traditional considerations such as rent and location.
Rental evidence illustrates this divide. Prime CBD rents remained at approximately €32 per sqm per month during Q2, while CBRE recorded rents in Lisbon’s Expansion Area increasing to around €23 per sqm per month. Most other locations remained broadly stable. Over a longer period, Lisbon’s prime rents have also recorded substantial annual growth despite the decline in overall leasing during the first half, suggesting that weaker aggregate demand has not translated into widespread pressure on the best buildings.
The location and size of Q2 transactions provide further evidence that companies remain willing to make significant commitments when suitable offices become available. The CBD generated around 36% of quarterly take-up, while newer office districts also attracted a meaningful share of demand. Investment technology company iCapital committed to approximately 9,000 sqm at Fidelidade’s headquarters on Avenida Álvaro Pais, making it one of the largest transactions of the quarter. Other notable leases included approximately 3,470 sqm at República 24 and Boston Consulting Group taking around 3,230 sqm at Campo Novo.
The question facing Lisbon is therefore not simply whether the city has enough offices, but whether enough of its existing stock matches what major occupiers now require. An older vacant building with weaker environmental performance or outdated technical specifications does not necessarily compete directly with a newly constructed office, even when both properties appear within the same city-wide availability statistics.
That distinction will become more important as Lisbon’s development pipeline reaches the market. Approximately 47,900 sqm of new office accommodation was completed during Q2 alone, while around 204,000 sqm is already being built. Total expected deliveries over the next three years approach 273,000 sqm. Only around one-fifth of the space currently under construction has already been secured by occupiers, meaning developers will be delivering a substantial amount of new accommodation into a market where first-half leasing has declined.
This does not necessarily mean Lisbon is heading towards general oversupply. New buildings will compete most directly for companies seeking high-quality offices, while older properties could face a different challenge. As modern developments increase the choices available to occupiers, landlords of ageing buildings may come under greater pressure to refurbish and reposition their assets if they want to compete successfully for larger corporate tenants.
The result could be a widening performance gap within Lisbon’s office stock. Well-located, efficient buildings offering modern specifications may continue supporting stronger rents even if overall vacancy increases, while properties requiring substantial capital expenditure could find it progressively more difficult to attract occupiers without investment. For developers, this places greater importance on delivering the right specification rather than simply adding floor space. Investors must similarly distinguish between buildings where refurbishment can restore competitiveness and assets where the cost of modernisation may become difficult to justify.
Lisbon consequently presents an unusual office-market picture in 2026. Leasing volumes have declined, new construction is increasing and estimates show meaningful vacant space across the city, yet prime rents remain resilient and companies continue committing to substantial leases when appropriate buildings become available. As more projects are completed, the difference between desirable and secondary offices is likely to become increasingly visible. Lisbon’s next office challenge may therefore be less about how much vacant space the city has and more about how much of that space companies still consider worth occupying.
Source: CIJ.World Research & Analysis Team