Monday, 14 September 2026
Japan’s retail property market is moving into a period where improving existing shopping centres is becoming more important than continually adding new ones. With development costs rising and the country already possessing an extensive retail network, landlords are increasingly directing investment toward refurbishment, new tenant combinations and additional services designed to generate more value from established properties. The change is taking place against a surprisingly resilient consumer backdrop. Japan had just over 3,000 shopping centres at the end of 2025, yet only 18 new centres opened during the year. Despite the limited amount of new development, nationwide shopping-centre sales climbed to approximately ¥33.1 trillion (approx. €178.50 billion), reaching their highest annual level.
The contrast is significant for property investors. Growth in retail spending is increasingly being captured by existing centres rather than depending on the construction of additional floor space. This gives landlords a stronger incentive to modernise successful properties and reconsider how older centres are used. Refurbishment is therefore becoming an increasingly important investment strategy. Owners can replace weaker tenants, introduce new retail concepts, upgrade dining areas and improve common spaces without taking on the cost and development risk associated with creating an entirely new shopping centre.
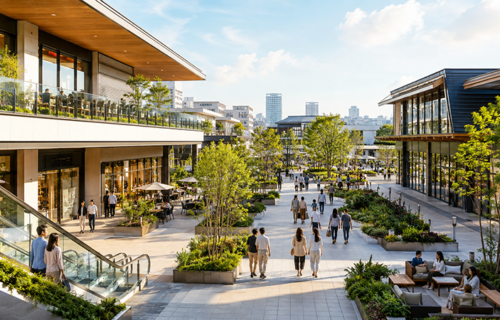
Japan’s largest retail-property operators are already following this approach. Established centres across Greater Tokyo are undergoing significant renovation programmes as landlords attempt to respond to changing consumer expectations while preserving the advantages of proven locations. The changes extend beyond conventional shops. Food, leisure, entertainment, fitness and services are becoming increasingly important components of the tenant mix. The objective is to provide customers with more reasons to visit and to increase the amount of time they spend at the property.
This represents an important evolution in the role of the shopping centre. A successful property increasingly needs to function as part of everyday community life rather than simply as a destination for occasional purchases. Japan’s spending patterns reinforce this shift. Supermarkets, convenience stores and pharmacies continue to generate substantial sales because they provide products that households purchase regularly. These businesses can therefore bring recurring customer traffic to properties even when spending on more discretionary categories becomes weaker.
For landlords, that frequency is valuable. A supermarket or pharmacy can attract consumers several times a week, while restaurants, fashion, leisure and entertainment businesses can capture additional spending once those customers are already at the property. Convenience stores demonstrate the importance of this behaviour particularly clearly. Their extensive nationwide network is built around accessibility and frequent visits, with locations concentrated close to homes, offices, railway stations and transport routes.
Their role extends well beyond traditional small-format food retailing. Japanese convenience stores have developed into local service points that combine everyday purchases with functions that encourage repeated visits. From a real estate perspective, their importance comes from the value they place on location. Individual stores may occupy relatively small premises, but the success of the model depends on maintaining a dense network of easily accessible sites.
A similar principle increasingly applies to larger neighbourhood and suburban retail properties. Consumers may still visit major shopping centres for fashion, restaurants or entertainment, but centres that also provide groceries, healthcare, fitness and everyday services can become more closely integrated into regular household routines. Japan’s demographic structure makes this increasingly relevant. An ageing population places greater importance on accessibility, while smaller households and changing lifestyles can favour retail locations where several requirements can be satisfied during a single visit.
Properties that are convenient to residential areas and public transport may therefore have an advantage, particularly where customers do not want to travel significant distances for everyday purchases. This does not mean Japan’s traditional destination retail market is weakening. The country’s leading shopping streets remain exceptionally competitive, particularly in Tokyo. Prime locations continue to attract domestic and international brands, supported by tourism and strong pedestrian traffic. Available premises remain scarce in several leading districts, while rents have continued to increase.
Japan is therefore developing several distinct retail investment markets at the same time. Prime urban streets are benefiting from global brand demand and international visitors, major shopping centres are increasing their emphasis on dining and entertainment, while neighbourhood and suburban properties are becoming more closely focused on regular local spending. For investors, this places greater emphasis on the individual characteristics of each property.
Size alone provides little indication of future performance. The strength of the surrounding population, access to transport, tenant productivity and the ability of the property to introduce new services are increasingly important. An older shopping centre in an established location can therefore remain highly competitive if its owner continues to invest in it. Many Japanese retail properties have operated successfully for decades because they have been repeatedly renovated rather than allowed to become obsolete. Tenant mixes have changed, interiors have been modernised and additional uses have been introduced as surrounding communities evolved.
Rising construction costs make this strategy even more attractive. Developing a completely new shopping centre requires expensive land, materials and labour, while suitable large sites can be difficult to assemble in metropolitan areas. Existing centres already possess infrastructure, transport connections, established customer bases and relationships with tenants. Investing in these properties can therefore provide a more predictable route to growth.
The approach is not without risks. Japan’s population is declining nationally, and some regional communities face significant long-term reductions in household numbers. Retail properties serving these markets may struggle to justify continued expansion. In some locations, owners could eventually need to reduce the amount of traditional retail space or introduce alternative functions to keep properties economically viable.
This creates an increasingly important distinction between assets. Centres serving stable or growing urban populations can continue attracting investment, while properties in weaker demographic areas will require more selective strategies. The ability to adapt becomes particularly valuable where the surrounding market is changing. Some shopping centres could gradually incorporate more healthcare, community services, entertainment or other non-traditional functions. Others may need substantial redevelopment to remain relevant.
This means the next phase of Japan’s retail property market is unlikely to be measured primarily by how many new shopping centres are built. Instead, performance will increasingly depend on what landlords can achieve with the extensive portfolio that already exists. The combination of limited new supply and resilient spending provides well-located existing centres with an important advantage. Owners capable of adapting their properties to changing consumer behaviour can potentially increase income without depending on continuous physical expansion.
Japan’s retail market is therefore moving from a development-led phase toward a more management-intensive investment cycle. For landlords and investors, the opportunity lies in identifying established properties where refurbishment, better tenants and additional services can increase productivity. The winners may not necessarily be the newest or largest shopping centres. They are more likely to be the properties that remain convenient, relevant and useful enough to become part of consumers’ everyday lives.
In one of the world’s most mature retail markets, the next source of property growth may increasingly come from reinventing what has already been built.
Source: © CIJ.World Japan Research & Analysis Team