Saturday, 19 September 2026
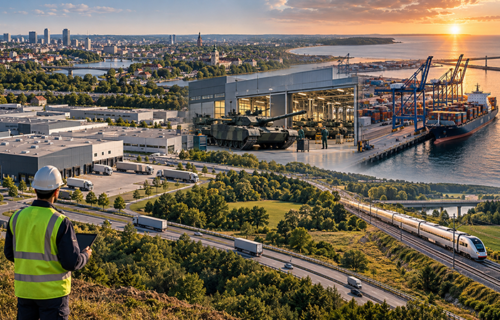
Lithuania’s industrial property market is entering a period in which factories, defence production and major infrastructure projects could become as important to future development as conventional logistics demand. Warehouses remain a significant part of the market, with logistics companies accounting for around 70% of demand for speculative industrial developments across Vilnius, Kaunas and Klaipėda during the second quarter of 2026. But some of the country’s largest new industrial investments are now being driven by manufacturing and defence rather than distribution.
This is beginning to broaden the geographical discussion around Lithuanian industrial property. Vilnius remains the country’s largest economic and employment centre and continues to generate substantial logistics demand. Kaunas has an established manufacturing base and strong connections towards Poland and Western Europe, while Klaipėda combines industrial activity with Lithuania’s principal seaport. Increasingly, however, investment decisions are also being influenced by defence production, transport corridors and the availability of industrial infrastructure.
One of the most significant projects is Rheinmetall’s ammunition plant at Baisogala in the Radviliškis district. Investment in the facility is expected to reach as much as €300 million, making it one of Lithuania’s largest new manufacturing projects. The plant is being developed and prepared for production, with output expected to increase progressively following the qualification process. Rheinmetall has also indicated that Lithuanian businesses will participate in construction and the future operation of the facility.
For the property market, this local involvement could prove as important as the factory itself. Large manufacturing facilities require transport, maintenance, storage, engineering and other supporting services. Some suppliers can continue operating from existing facilities elsewhere in Lithuania or abroad, while others may eventually decide that being closer to their customer provides an operational advantage.
If that happens at sufficient scale, Baisogala could begin developing an industrial ecosystem around an investment that initially appeared to be a single manufacturing project. That process is not guaranteed. The presence of one large factory does not automatically create a new industrial property market. Much will depend on the structure of Rheinmetall’s supply chain, the proportion of components sourced locally and whether suppliers require physical operations close to the plant.
Kaunas provides a more established foundation for such growth. Lithuania Defence Services, the joint venture involving Rheinmetall and KNDS Deutschland, is moving ahead with a Leopard 2A8 assembly and maintenance facility in the Kaunas Free Economic Zone. A construction agreement has been signed with YIT Lietuva for a facility of approximately 13,000 sqm, with the construction contract worth close to €30 million. Work is scheduled to progress through 2026 and 2027, with completion planned for late 2027.
The project adds another layer to Kaunas’s industrial proposition. The city already benefits from a substantial manufacturing sector, the free economic zone and motorway connections towards Vilnius, Klaipėda and Poland. Its position on Lithuania’s north-south transport routes also gives it strategic importance for companies moving components and finished products between the Baltic states and the rest of the European Union.
Defence production could strengthen that existing industrial base rather than create one from scratch. Tank assembly and long-term maintenance require far more than an assembly hall. Metalworking, electronics, engineering, vehicle components, specialist maintenance, storage and transport all form part of a wider defence-industrial chain. Lithuania’s opportunity is to capture a larger proportion of those activities domestically.
Rail Baltica could reinforce Kaunas’s position over the longer term. The new European-gauge railway is intended to connect Lithuania more directly with Poland and the wider continental network. As sections are completed, the project should improve the country’s north-south connectivity and potentially make central Lithuania more attractive to manufacturing and logistics operations serving several European markets.
The industrial implications will depend on how companies actually use the infrastructure. Rail investment alone does not create property demand, but improved connectivity can become an important factor when manufacturers compare locations for future plants and distribution operations.
Klaipėda is developing along a different path. The Port of Klaipėda plans to invest approximately €775 million through 2029, with close to €600 million associated with development of its southern area. The expansion is expected to create approximately 100 hectares of new territory and around 1.3 kilometres of additional quay infrastructure. Including expected private investment, the wider development could ultimately exceed €1 billion.
Importantly, the project has moved beyond long-term planning. Preparatory work was under way during the summer of 2026 as the port began moving the expansion towards physical construction. For commercial property, the significance lies in the land and infrastructure being created around the port.
New territory with maritime, road and railway connections could accommodate activities ranging from cargo handling and logistics to manufacturing, processing and marine engineering. The port is also considering both commercial and strategic uses, increasing the range of potential occupiers. This gives Klaipėda an industrial proposition that neither Vilnius nor Kaunas can replicate: direct access to international shipping combined with new development territory.
Lithuania is therefore developing several distinct industrial locations rather than a single national market. Vilnius remains important for distribution because of its population, employment base and concentration of businesses. Kaunas increasingly combines logistics with manufacturing and defence-related activity. Klaipėda is expanding its port-led industrial economy. Baisogala introduces the possibility of strategic manufacturing generating demand in a location previously outside the main institutional property markets.
Whether investors follow these developments will depend on more than headline investment announcements. Manufacturing companies require sites with sufficient electricity, water, transport access and planning certainty. For some industries, the availability and timing of grid connections can be more important than the price of land itself.
Labour is another potential constraint. Lithuania has a relatively small population, meaning major factories can create competition for engineers, technicians and production employees. Locations with access to larger labour catchments, universities and technical education could therefore have an advantage.
The same issue could eventually affect residential and commercial development. If new industrial locations generate substantial employment, workers will require housing, shops, services and accommodation. Those secondary property effects could become particularly important around smaller municipalities where the arrival of several hundred specialised jobs can have a proportionately large economic impact.
For institutional property investors, much of the opportunity may emerge later. Highly specialised factories are often developed directly for their occupiers because the buildings are designed around specific manufacturing processes. As these facilities mature and establish predictable operations, some may eventually become suitable for sale-and-leaseback transactions or other investment structures. More conventional warehouses, supplier facilities and service properties around them could become investible sooner.
There are nevertheless reasons for caution. Lithuania’s logistics industry continues to face pressure from subdued freight growth and excess transport capacity even while logistics companies remain active occupiers of modern industrial space. Strong property demand in individual locations should therefore not be interpreted as evidence that every part of the transport sector is expanding equally.
The same caution applies to defence. Lithuania has secured several major industrial projects, but it is too early to describe Baisogala or other emerging locations as established property clusters. The real evidence will come from what happens around the headline investments.
If suppliers begin acquiring land, manufacturers open component facilities and logistics companies establish dedicated operations nearby, the effect on Lithuania’s industrial property market will become much more substantial. The country’s industrial geography would then no longer be defined primarily by warehouses serving Vilnius, Kaunas and Klaipėda.
Instead, Lithuania could develop a network of increasingly specialised industrial locations shaped by defence production, manufacturing expertise, European transport connections and access to the Baltic Sea. The factories are already arriving. The next question is whether an entirely new layer of property development follows them.
Source: CIJ.World Research & Analysis Team