Monday, 14 September 2026
Brazil has one of the largest residential rental populations in the world, yet professionally owned rental housing remains a remarkably small part of its property investment market. Almost 19 million permanent homes in the country are rented, and the number has increased substantially over the past decade. Despite that enormous demand base, large-scale ownership of apartment buildings specifically developed or acquired for long-term rental remains at an early stage. This creates one of the clearest mismatches in Brazilian real estate: millions of households already rent their homes, but institutional investors own only a tiny fraction of the properties in which they live.
The opportunity is consequently much larger than the existing institutional market suggests. Brazil does not need to create a culture of renting before professionally managed housing can expand. The demand already exists. The challenge is turning an overwhelmingly fragmented market of individually owned apartments into portfolios capable of attracting pension funds, investment managers, property companies and other long-term capital.
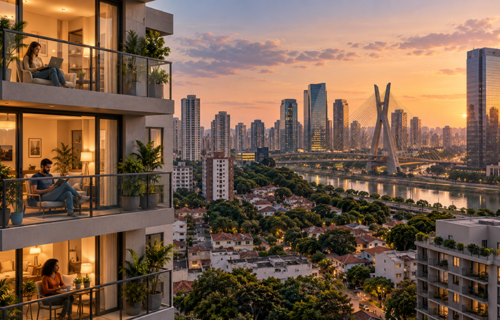
São Paulo has become the principal testing ground. The city combines an enormous population, expensive home ownership, major employment centres, universities and a highly mobile professional workforce. These conditions favour rental housing, particularly in locations with good public transport and access to employment. Yet even in São Paulo, where most of Brazil’s emerging institutional rental stock is concentrated, professionally managed apartment buildings remain a very small part of the overall housing market.
Conventional multifamily provides the most obvious opportunity. Instead of developing apartments for individual sale, an investor retains ownership of the entire building and operates it as a rental property. Residents receive professionally managed accommodation while the owner receives recurring income from hundreds of leases within a single asset. The model is well established in the United States and increasingly important across European and Asian property markets, but it remains relatively new as an institutional investment strategy in Brazil.
One obstacle is the structure of Brazil’s existing housing stock. Apartments have traditionally been developed and sold individually, producing buildings containing dozens or hundreds of different owners. Institutional investors cannot easily acquire large portfolios of existing rental homes because ownership is fragmented across millions of households. Building scale therefore often requires developing properties specifically for rental, purchasing entire developments or gradually assembling portfolios. Each route requires capital, time and specialist management.
Brazil’s financing environment creates another difficulty. Rental housing competes for investment capital with domestic fixed-income products that can provide attractive returns without construction, leasing or operating risk. Investors committing money to a residential rental development must therefore believe that the combination of income growth and long-term property appreciation will adequately compensate them for the additional complexity. This becomes particularly important because the capital remains invested for much longer than in a conventional residential development. A developer selling apartments can recover capital as units are completed and transferred to buyers. An institutional rental owner retains the building and relies on income generated over many years.
Land economics add another challenge. The locations most attractive to renters are frequently the places where development sites are most expensive. Proximity to employment, metro and rail stations, universities, restaurants and services can support stronger rents, but it also increases the price of land. Developers therefore need to find a balance between density, apartment size, construction cost and the rent residents can realistically afford.
This helps explain the importance of smaller apartments within emerging professionally managed residential projects. Compact units allow more homes to be created on expensive urban sites and can appeal to students, younger professionals and single-person households. But simply reducing apartment sizes does not create a successful rental product. Buildings increasingly need attractive common areas, reliable maintenance, digital leasing systems, security and services that differentiate them from individually owned apartments available elsewhere in the market.
Student accommodation could provide another route towards institutional scale. Brazil has an enormous higher-education population, but dedicated professionally operated student housing remains limited compared with mature international markets. Universities create concentrated and relatively predictable accommodation demand, potentially allowing investors to develop buildings specifically designed around students rather than adapting conventional apartments.
The opportunity is highly dependent on location. Successful student accommodation requires proximity or convenient transport to major campuses, sufficient numbers of students living away from their family homes and rents that remain competitive with alternative accommodation. São Paulo offers obvious possibilities because of the scale of its university sector, but regional university cities may also support projects where lower land costs improve development economics.
Co-living addresses a related but broader demographic. Younger professionals, graduates arriving in large cities and workers seeking flexibility may value furnished accommodation, shorter commitments and shared amenities. The model can potentially generate more income from a building than conventional long-term apartments, but it also introduces substantially greater operating complexity. Higher tenant turnover, furnished units, communal areas and additional services mean that successful co-living businesses require management capabilities closer to hospitality than traditional residential letting.
This operational requirement is important across the entire emerging living sector. Multifamily, student housing and co-living cannot simply be approached as buildings containing leases. Their performance depends on attracting residents, maintaining occupancy, setting rents, controlling operating expenses, responding to maintenance issues and delivering a consistent customer experience. As portfolios expand, technology and data become increasingly important because operators must manage thousands of individual leases rather than a relatively small number of corporate tenants.
Scale can improve those economics. A company operating one residential building must support management, technology and marketing infrastructure from a relatively small income base. A platform operating thousands of apartments across multiple properties can spread those costs much more efficiently. This is one reason the creation of operating platforms may eventually prove more important than individual residential developments.
The absence of scale currently creates another challenge for institutional investors: limited market liquidity. Investors need confidence not only that they can develop or acquire residential portfolios, but also that there will eventually be buyers for those assets. A market containing relatively few large owners naturally produces fewer portfolio transactions, fewer comparable prices and fewer established exit routes. Investors entering an immature market may consequently demand higher returns.
This produces a familiar problem for emerging property sectors. Institutional investors want evidence of liquidity before committing substantial capital, while liquidity cannot develop until enough institutional investors have entered the market. Early participants therefore take greater market and operating risk but could also benefit if rental housing eventually becomes a recognised mainstream allocation.
Standardisation will be important in reaching that point. Mature investment sectors allow investors to compare vacancy, rents, operating expenses, tenant retention and returns across portfolios. Brazil’s institutional rental market is still developing the depth of performance data required to make those comparisons easily. As more projects operate through complete leasing cycles, investors should gain a clearer understanding of achievable rents, resident turnover, maintenance costs and long-term income growth.
Geographic diversification represents another major test. São Paulo currently dominates professionally managed rental housing, but Brazil is a continental-scale country containing numerous large metropolitan economies. Rio de Janeiro, Brasília, Belo Horizonte, Curitiba and other cities have substantial renter populations, universities and employment centres, yet their residential economics differ significantly. A strategy that works in São Paulo cannot automatically be replicated elsewhere.
For the sector to become genuinely institutional, investors will eventually need to demonstrate that portfolios can operate across several cities. That could create opportunities to build national platforms rather than collections of isolated projects. Different residential formats may also suit different locations. Conventional multifamily could work around major employment centres, student accommodation around university clusters and more flexible living formats in neighbourhoods attracting younger mobile workers.
The potential extends beyond purpose-built rental developments. Investors may eventually find opportunities to acquire existing residential buildings, unfinished projects or properties originally intended for individual sale and convert them into professionally managed rental portfolios. Distressed or incorrectly positioned developments could provide another route into the sector if acquisition prices allow rental returns to compete with alternative investments.
Affordability, however, remains fundamental. Institutional rental housing cannot grow indefinitely by targeting only wealthy residents willing to pay premiums for amenities. Brazil’s enormous rental market spans a much wider range of household incomes. The greatest long-term opportunity could therefore emerge when investors find development and operating models capable of providing professionally managed housing at rents accessible to a broader section of the population.
This makes construction efficiency increasingly important. Standardised designs, modular elements, smaller units, efficient common areas and careful site selection could help reduce the cost of delivering rental housing. Investors able to repeat similar projects across multiple locations may also achieve economies that individual developments cannot.
The investment case ultimately rests on the extraordinary difference between the size of Brazil’s rental population and the size of its institutional market. The country already has millions of tenants, enormous cities, substantial universities and a growing need for professionally managed urban housing. What it lacks is a mature investment structure capable of aggregating that demand into portfolios of sufficient scale.
Multifamily, student accommodation and co-living could all become part of that structure, but growth is unlikely to be automatic. High financing costs, expensive development land, fragmented ownership, operating complexity and limited liquidity remain significant obstacles. The successful platforms will need to solve several of these problems simultaneously rather than relying solely on rising rental demand.
If they do, residential property could become one of the most significant areas of expansion for Brazilian institutional real estate. The opportunity is not based on predicting that Brazilians will suddenly become renters. They already are. The opportunity lies in determining whether institutional capital can finally build an investment market large enough to reflect the scale of the rental market that already exists.
Source: CIJ.World Research & Analysis Team