Wednesday, 16 September 2026
Artificial intelligence is moving rapidly from systems that answer questions towards software capable of taking actions. One of the most consequential next steps is financial: giving AI agents the ability to pay for information, services and digital tools without requiring a person to intervene in every transaction. That emerging market was the focus of a discussion at AI4 2026 in Las Vegas between Erik Reppel, creator of the x402 payment protocol and former Head of Engineering at Coinbase Developer Platform, and Aaron Stanley of Promenade Advisory. Their conversation highlighted how the convergence of AI, digital payments and blockchain infrastructure could create a new machine-to-machine economy in which software buys what it needs in order to complete a task.
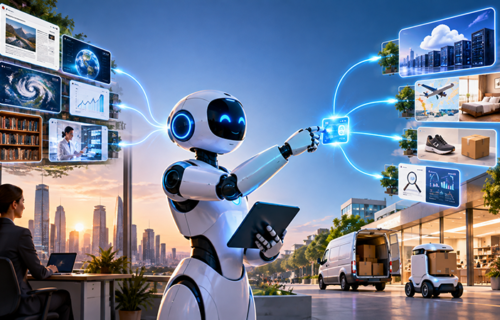
The concept is different from the conversational shopping experiences increasingly appearing in consumer e-commerce. In that model, a person might ask an AI assistant to recommend running shoes, compare several options and then manually approve a purchase. Autonomous commerce goes further. While completing the research, the agent itself could pay for access to specialist data, premium reviews, computing capacity or another digital service without returning to the user for approval each time. This distinction could become economically important because AI agents increasingly depend on external information and tools. A general-purpose model may be able to answer many questions from its existing knowledge, but specialised tasks often require current data, proprietary databases, premium search, software interfaces or additional computing resources. Today, connecting those services usually requires a developer to create accounts, manage subscriptions, provide API keys and establish billing relationships in advance.
Reppel argues that a payment system designed for machine-to-machine transactions can remove much of that friction. Rather than an AI agent being limited to the tools configured by its developer, it can potentially discover a service, receive a price, pay for access and continue working automatically. The x402 protocol was developed to address that problem. Its name derives from HTTP status code 402, which was reserved decades ago for “Payment Required” but never became a widely used part of the web. Coinbase revived the concept by developing an open protocol that allows payments to be incorporated directly into normal internet interactions.
Coinbase formally introduced x402 in May 2025 as an internet-native payment standard allowing applications, APIs and AI agents to make payments directly through HTTP. The initial implementation focused heavily on stablecoins, but the broader ambition is not to make one payment method mandatory. Instead, x402 is intended to separate the payment request from the particular financial rail used to settle it. That could eventually allow agents to choose between stablecoins, payment cards and other methods according to the transaction. A large consumer purchase might still be more suitable for a credit card because of consumer protections, insurance or rewards. A payment of only a few cents for a single database query may make more economic sense on another rail.
This becomes particularly important for micropayments. The commercial internet has largely developed around advertising, subscriptions and relatively large individual purchases partly because conventional payment economics make extremely small transactions unattractive. Card transactions normally include fixed processing costs as well as percentage-based fees. As the purchase amount becomes very small, those costs can represent an impractical share of the transaction. AI agents could create demand for an entirely different type of payment behaviour. An agent researching a problem may value a particular piece of information at only a few cents. It may want to pay for one search result, one article, one API call or several seconds of specialised computing rather than purchasing an entire monthly subscription.
If payment infrastructure can handle those transactions economically, previously difficult business models become possible. This could have particularly important consequences for publishers and information providers. Generative AI can summarise information without sending users directly to the websites that produced it. That weakens advertising and affiliate models that depend on human visitors clicking through to the original publisher. A machine-payment model offers a different possibility. Rather than relying entirely on human traffic, publishers could potentially charge AI agents directly for access to premium articles, datasets, analysis or archives. A consumer might continue receiving an AI-generated answer, while the agent pays several information providers in the background to assemble that answer.
The economics could resemble wholesale information markets more than conventional media subscriptions. Instead of asking every consumer to maintain dozens of separate subscriptions, an AI assistant could purchase individual units of information only when they are useful. Whether publishers ultimately embrace that model remains uncertain, but the infrastructure is already beginning to appear. Coinbase has demonstrated x402 integrations allowing agents to purchase API access and other digital services on a pay-per-use basis without conventional API keys or account creation.
The x402 ecosystem is also expanding beyond its original Coinbase environment. In 2026, the protocol moved towards a foundation model intended to provide broader and more neutral governance. Participation from major payments, technology and infrastructure companies suggests that agentic payments are increasingly being treated as a wider payments-infrastructure issue rather than simply another cryptocurrency application.
Open standards may prove particularly important if autonomous commerce grows. No retailer, bank, technology provider or AI developer is likely to want a future in which one company controls the only infrastructure through which agents can make payments. Internet protocols historically became powerful precisely because competing businesses could build on common standards while retaining control over their own services. A neutral payment protocol could perform a similar role for autonomous software. Merchants could specify which methods they accept, while agents select whichever compatible payment option best suits the transaction.
That flexibility could become important because machine commerce will not consist of a single type of purchase. An AI agent arranging a business trip might pay for search access, buy specialised travel data, reserve a hotel and purchase an airline ticket. Each transaction carries different economics, regulatory requirements and consumer protections. Some may justify stablecoin settlement because of speed and transaction costs. Others may remain firmly within conventional banking and card networks. The infrastructure therefore needs to accommodate several payment rails rather than assume that one system will replace all others.
Reppel described another potentially significant consequence: AI agents could become more dynamic. Most agents today have a relatively fixed collection of capabilities. Developers decide which services they can access, configure the APIs and establish the required subscriptions. If the agent encounters a problem requiring a service that has not been configured, it may simply be unable to continue. A machine-payment layer could allow the agent to acquire capabilities as required. If it needs specialist weather information, advanced search, translation or another analysis tool, it could discover an available service and pay for one-time access. The set of functions available to the agent would therefore expand as new services entered the market without requiring the user to configure each one manually.
That begins to resemble an application marketplace operated primarily by software rather than people. Discovery infrastructure is already developing around this idea, allowing agents to identify services that can be purchased programmatically across areas including data, search, infrastructure, inference and other digital functions. If these marketplaces expand, software agents could eventually assemble their own combinations of tools according to the task they have been asked to complete.
This could also alter software pricing. The software-as-a-service economy has largely been built around subscriptions. Companies pay monthly or annual fees because establishing a billing relationship for every individual software interaction would be cumbersome. AI agents may favour consumption-based purchasing instead. An agent might pay for 20 searches today, use nothing tomorrow and purchase a different service the following week. For occasional users, this removes the need to maintain subscriptions to products they rarely use.
Reppel suggested that providers may even be able to charge slightly more per individual interaction because customers are paying for convenience and avoiding long-term commitments. Frequent users could then move naturally towards conventional subscriptions once recurring usage makes them more economical. That creates a possible two-stage commercial model: low-friction pay-per-use access for discovery followed by subscriptions for high-volume customers.
For software providers, this could reduce one of the largest barriers to acquiring new customers. A potential user would no longer necessarily need to create an account, enter payment details and agree to a monthly plan before testing a product. An AI agent could make a small payment, evaluate the service and continue using it if the result justified the price. Machine customers could therefore become a new route to market.
This also changes what it means to design a digital product. Companies have historically built websites and applications for human users. Increasingly they may also need to make products readable, discoverable and purchasable by software agents. That means publishing machine-readable pricing, clearly describing capabilities, exposing inventory or service availability and making it possible for automated systems to authenticate and transact securely.
The transformation could eventually reach beyond purely digital products. Consumer shopping, travel, logistics, financial services and procurement could all become partially agent-driven, but the timetable is likely to differ significantly by category. Low-value digital services are an obvious early market because transactions can be completed entirely online and the financial risk is limited. Autonomous purchasing of physical goods creates additional questions involving delivery, returns, fraud, liability and consumer authorisation.
Business-to-business commerce may also move relatively quickly. Corporate procurement frequently involves repetitive transactions governed by established budgets and approved suppliers. An agent operating within defined limits could potentially obtain prices, compare suppliers and execute routine purchases automatically. As these systems develop, financial controls will become as important as payment capability. Businesses will need to determine how much an AI agent can spend, which suppliers it may use, what categories are permitted and when a human must approve a transaction.
The challenge therefore is not simply giving AI access to a wallet. It is creating programmable authority. An organisation might allow an agent to spend several cents on information without approval, several hundred euros on routine procurement within an approved supplier network, but require human authorisation for larger commitments. Financial governance will need to become embedded in the agent itself.
This is likely to create new opportunities for banks, card networks, payment processors and financial technology companies. The financial industry has decades of experience with fraud detection, authorisation, identity and transaction monitoring. Agentic commerce introduces a new participant into those systems: software acting on behalf of a person or organisation. Payment companies therefore need to establish not only whether sufficient funds are available, but whether the AI agent itself has permission to make the transaction.
That helps explain why traditional payment groups are becoming involved so early. The future market is not necessarily a competition between blockchain and credit cards. It may be a competition over who provides the identity, authorisation, settlement and risk infrastructure connecting autonomous agents to the financial system.
The scale of that future market remains impossible to determine. Forecasts describing agentic commerce as a multi-trillion-dollar opportunity depend on assumptions about how quickly autonomous agents become reliable enough for consumers and companies to delegate meaningful spending authority. Adoption remains early. Even at an AI-focused conference, only a small number of attendees indicated that they had personally allowed an agent to transact for them.
Yet the underlying direction is significant. Search became a standard capability for AI assistants because an agent without access to current information quickly became less useful. Payments could follow a similar trajectory. Once agents can routinely pay for information and services, financial capability may become another expected component of an intelligent digital assistant.
For businesses, the strategic question is therefore broader than whether they should accept cryptocurrency or implement one particular payment protocol. It is whether their products and services will be accessible to customers that are increasingly represented by software. The internet was designed around people browsing websites, reading advertisements, clicking buttons and entering payment information. An agent-driven internet works differently. Software does not need graphical interfaces, may not respond to advertising and can compare large numbers of providers before completing a transaction.
That could undermine some of the assumptions behind today’s digital economy while creating entirely new markets. Publishers may sell individual pieces of information rather than advertising impressions. Software companies may sell individual API calls alongside subscriptions. Data providers may receive revenue from agents that discover their services moments before purchasing them. AI systems may automatically assemble combinations of paid services that no developer explicitly configured in advance.
None of this means conventional commerce disappears. Humans will continue to make purchasing decisions, payment cards will remain important and subscriptions will continue where they offer better economics. What changes is the customer base. For the first time, businesses may increasingly be selling not only to people and other companies but directly to autonomous software operating with its own purchasing authority.
If that develops at scale, agentic commerce will not simply become another feature within artificial intelligence. It could become a new economic layer of the internet, where information, computing resources and eventually physical goods are discovered, priced and purchased by machines in real time. The important development is therefore not that an AI agent can now hold a wallet. It is that the infrastructure is beginning to emerge through which millions of software agents could eventually participate in commerce without being individually configured for every transaction.
That possibility turns AI from a consumer of information into an economic participant and may force companies to rethink who, or what, their next customer actually is.
Source: CIJ.World Research & Analysis Team