Monday, 2 November 2026
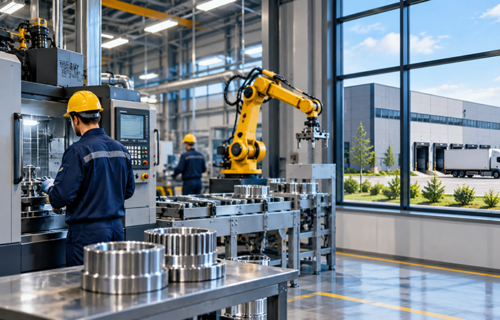
Poland’s manufacturing industry showed signs of improvement in October 2026, following an extended period of declining business activity. The latest survey of industrial companies indicated that conditions had stopped deteriorating for the first time in almost a year and a half, offering a more encouraging outlook for businesses involved in production, distribution and industrial property development.
According to figures published by S&P Global on 2 November, Poland’s manufacturing Purchasing Managers’ Index (PMI) increased to 50.0 in October from 49.0 in September, reaching its highest level in approximately 18 months. The index measures changes in business conditions across the manufacturing sector, with readings below 50 indicating a decline and figures above that level suggesting growth. October’s result therefore points to stabilisation rather than a clear expansion in industrial activity.
The improvement was supported by more favourable developments in overseas orders and employment. However, manufacturers continued to experience weakness in overall demand, indicating that the recovery remains uneven. While some companies reported better conditions in international markets, domestic and export business combined had not yet returned to sustained growth. This suggests that manufacturers remain cautious about increasing production capacity or committing to major investments.
Operating expenses also continued to present difficulties for industrial businesses. Rising costs for materials and other production requirements placed additional pressure on manufacturers, particularly those unable to recover these increases through higher selling prices. Companies assessing future investments must therefore balance expectations of improving demand against the financial implications of production, energy, transport and financing costs.
There were nevertheless indications that some manufacturers were preparing for a possible improvement in business activity. Purchases of production materials increased for the first time in five months, while inventories of inputs continued to grow. These developments suggest that businesses may be positioning themselves for future orders, although the continued reduction in unfinished work indicates that production capacity remains sufficient to meet current demand. Expectations for output over the coming year also weakened compared with September, highlighting the uncertainty surrounding the pace of recovery.
For Poland’s commercial property market, the stabilisation of manufacturing activity represents a potentially positive development. Industrial companies are important occupiers of factories, production facilities, warehouses and distribution centres, and their investment decisions influence demand for industrial and logistics accommodation. Stronger manufacturing orders could eventually encourage businesses to expand their operations, increase storage requirements or invest in additional production facilities. However, the latest survey does not provide evidence of an immediate increase in property leasing or development commitments.
The implications are particularly relevant for industrial developers and investors monitoring occupier demand across Poland’s established manufacturing and logistics regions. Companies may initially respond to improving orders by making greater use of existing facilities rather than acquiring additional space. Decisions concerning expansion are also likely to depend on labour availability, energy costs, access to transport infrastructure and confidence in future demand. As a result, improvements in manufacturing indicators may take time to influence industrial property transactions and construction activity.
October’s PMI result exceeded market expectations of approximately 49.4 and brought an end to 17 consecutive months in which the index remained below 50. Although this represents an encouraging change in Poland’s industrial performance, the continued weakness in new orders and pressure on operating costs suggest that the sector has not yet entered a sustained period of growth. For developers, landlords and investors, the coming months will be important in determining whether the improvement develops into stronger industrial investment, additional employment and increased demand for manufacturing and logistics space.