Wednesday, 14 October 2026
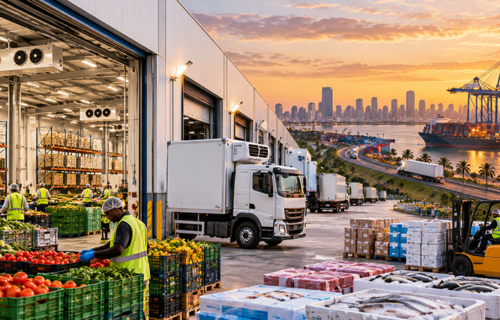
Africa’s expanding cities and changing food distribution networks are creating demand for a logistics property segment that remains relatively underdeveloped across much of the continent. Refrigerated warehouses are becoming increasingly important as food producers, retailers, importers, exporters and pharmaceutical distributors require more reliable temperature-controlled supply chains.
The investment case extends well beyond Africa’s warm climate. Rapid urbanisation is concentrating millions of consumers in large metropolitan areas while food production frequently takes place hundreds of kilometres away. Moving fresh produce, meat, dairy products and other perishable goods between farms, processing facilities and urban markets requires a combination of refrigerated transport, storage and distribution infrastructure that remains incomplete in many countries.
The consequences can be substantial. Nigeria’s cold-chain industry association estimated that between 30 million and 40 million tonnes of food were lost in 2025, representing an economic value of approximately NGN 3.5–5 trillion. Although these are industry estimates rather than official national statistics, they demonstrate the potential economic value of improving storage and distribution infrastructure.
Investment is beginning to respond. Ghana expanded cold-storage capacity at Kpone in Greater Accra during 2026 as part of efforts to strengthen domestic food production and distribution. Retail investment is also increasing demand for modern warehouse infrastructure, including refrigerated space, as larger chains expand their distribution networks.
Egypt is pursuing the sector on a larger logistics scale. A strategic warehouse completed at Fayoum in 2026 provides capacity for approximately 75,000 pallets and includes chilled and frozen areas. Further large distribution facilities incorporating temperature-controlled space are also being developed, showing how cold storage is increasingly becoming part of mainstream logistics infrastructure rather than a separate specialist facility.
Similar opportunities are emerging around ports and agricultural production centres. Plans for a major logistics development near the Port of Abidjan include refrigerated warehouses alongside conventional storage, food processing and commercial facilities. In Rwanda, cold-chain infrastructure is being incorporated into the development of the Gabiro agribusiness hub, creating a potential link between agricultural production, processing and distribution.
Morocco provides a more developed example. Tanger Med combines refrigerated storage with extensive logistics infrastructure and international shipping connections. This type of integrated model could become increasingly important elsewhere in Africa because successful cold chains depend on more than warehouse capacity. They require reliable transport, electricity and connections between producers, distribution centres and end markets.
Power supply remains one of the largest barriers. Unlike conventional warehouses, refrigerated facilities require continuous electricity to protect the goods they contain. Unreliable grids can force operators to invest in backup generation, solar power, batteries and other energy systems, increasing development and operating costs. Cold-storage investment is therefore closely connected with improvements in Africa’s wider energy infrastructure.
The sector also requires considerably more capital and technical expertise than conventional warehousing. Refrigeration equipment, insulation, monitoring systems and higher electricity consumption increase both construction costs and operational complexity. These requirements may restrict speculative development, but they also create higher barriers to entry and opportunities for specialist developers, operators and infrastructure investors.
Cold storage is consequently becoming part of the broader evolution of African logistics real estate. Population growth, modern retail, agricultural exports, food processing and pharmaceutical distribution are all increasing demand for facilities capable of maintaining controlled temperatures throughout the supply chain.
The strongest opportunities are likely to emerge where several of these drivers meet: large cities, ports, agricultural regions and major transport corridors with dependable electricity. As Africa’s supply chains modernise, refrigerated logistics could move from a persistent infrastructure shortage into one of the continent’s more important specialist property growth markets.
Source: © CIJ.World Africa Research & Analysis Team