Wednesday, 14 October 2026
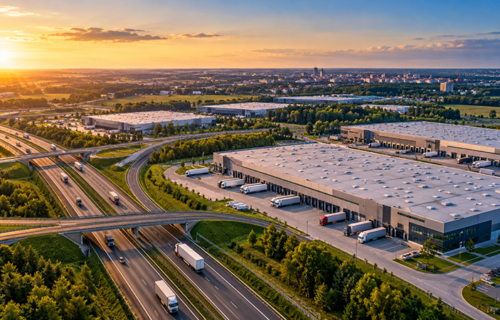
Central Poland’s industrial property market entered the final quarter of 2026 with significantly less vacant warehouse space, while development continued across Łódź and surrounding logistics centres. Research covering the first nine months of the year indicates tightening availability, with occupiers increasingly assessing locations according to transport connections, operating costs and workforce access. Stryków, Zgierz and Piotrków Trybunalski remain important alternatives to Łódź, particularly for businesses requiring extensive distribution and manufacturing facilities.
According to REDD’s third-quarter 2026 research, Central Poland contained approximately 5.94 million sqm of modern warehouse accommodation at the end of September. The regional vacancy rate declined to 3.9%, representing a reduction of 5.1 percentage points compared with September 2025. Available space fell by approximately 270,900 sqm over the year to 230,600 sqm. By comparison, Poland’s national vacancy rate stood at 6.4%, with approximately 2.71 million sqm available for occupation.
Construction continued despite declining availability. Approximately 263,600 sqm of warehouse space was completed in Central Poland during the first nine months of 2026, while another 274,000 sqm remained under development at the end of September. Among the largest investments was a distribution complex for Media Expert in Łódź, where approximately 120,000 sqm had been completed and a further 80,000 sqm remained under construction. The project demonstrates that the regional capital continues attracting substantial logistics investment alongside surrounding municipalities.
Leasing activity presented a more moderate picture. REDD recorded approximately 487,800 sqm of transactions in Central Poland between January and September 2026, an increase of just 0.5% compared with the corresponding period of 2025. Nationally, leasing increased by 66% to approximately 3.81 million sqm. The figures suggest that Central Poland’s declining vacancy reflects a combination of existing occupier commitments, limited available supply and development activity rather than an exceptional increase in new leasing transactions.
The geographical distribution of industrial investment remains an important feature of the market. Newmark Polska’s October research identifies Łódź as the region’s principal economic centre, while established logistics locations continue attracting developers through motorway accessibility and available land. Newmark estimates regional warehouse stock at approximately 5.2 million sqm, compared with REDD’s 5.94 million sqm. The difference indicates that the two assessments use different coverage or measurement approaches, although the precise methodological distinction has not been established.
Stryków remains one of the region’s largest logistics centres, supported by its position near the A1 and A2 motorway intersection. Its warehouse stock exceeds one million sqm, while approximately 38,000 sqm was under construction according to Newmark. The location continues attracting industrial investment, including Corning Optical Communications’ expansion at SEGRO Logistics Park Stryków, where an additional production and distribution facility exceeding 35,000 sqm is being developed. The project illustrates how established manufacturing operations contribute to demand alongside logistics companies.
Zgierz has also developed into an important industrial location north of Łódź, with approximately 270,000 sqm of warehouse and production accommodation. Its proximity to the metropolitan workforce and major transport corridors supports further development. Projects including Hillwood Park Zgierz II, which delivered approximately 77,000 sqm in 2024, demonstrate the scale of investment already established outside the regional capital.
Further south, Piotrków Trybunalski benefits from connections to the A1 motorway and S8 expressway, together with comparatively competitive rents. AXI IMMO previously reported monthly warehouse rents of approximately €3.10–3.70 per sqm in Piotrków Trybunalski, compared with €4.00–4.60 in Łódź. REDD’s September 2026 assessment placed the average advertised rent across Central Poland at approximately €4.00 per sqm. These figures highlight the importance of accommodation costs, although transport expenses and workforce availability also influence location decisions.
Labour availability remains another consideration for industrial investment. Established logistics centres can face competition for warehouse employees, drivers and technical personnel, particularly where businesses operate multiple shifts. Access to public transport, commuting distances and local wage expectations may therefore influence development decisions. However, comparable employment data for individual municipalities is needed before recruitment difficulties can be identified as a confirmed driver of investment beyond Łódź.
Developers are also taking a more cautious approach to new construction. Across Poland, more than 60% of warehouse space under development at the end of September was already committed to occupiers or intended for owners’ own operations. Earlier AXI IMMO research identified a substantial reduction in speculative construction across Central Poland during 2025. This approach can limit future vacant supply, although it may reduce the availability of large facilities for companies seeking immediate occupation.
For investors, Central Poland’s vacancy rate of 3.9% suggests a relatively constrained market, potentially benefiting owners of existing modern facilities. However, conditions may differ considerably between individual logistics locations, depending on construction activity, occupier requirements and available accommodation. The absence of consistent vacancy figures for Łódź, Stryków, Zgierz and Piotrków Trybunalski makes it difficult to assess these differences precisely.
Central Poland’s warehouse sector is consequently entering a more selective phase of development. Łódź continues attracting major distribution investments, while surrounding logistics centres provide alternatives for businesses requiring motorway access, larger sites and competitive operating costs. With vacancy declining and leasing activity remaining relatively stable, future growth is likely to depend increasingly on developments supported by identifiable occupier requirements rather than widespread speculative construction.