Thursday, 12 November 2026
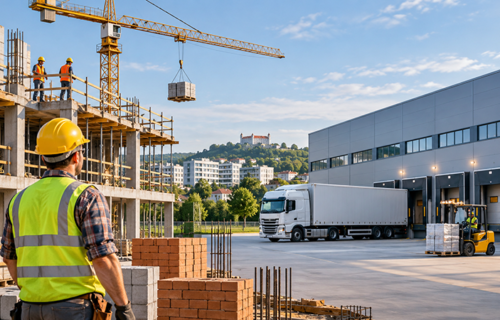
Slovakia’s construction sector recorded the strongest real wage growth among the country’s main economic activities in September 2026, adding to labour cost pressures facing property developers and building contractors. At the same time, transportation and storage businesses reduced employment despite increasing turnover, highlighting different operating conditions across sectors important to commercial real estate.
According to figures published by the Statistical Office of the Slovak Republic on 12 November, average nominal monthly wages in construction increased by 11.9% year-on-year, equivalent to real growth of 8.5% after adjusting for inflation. Construction employment also rose by 1.2%, making it one of only three monitored sectors to expand its workforce during September.
For residential and commercial developers, the increase in construction wages is relevant to project budgeting, particularly where labour represents a substantial share of building costs. Higher payroll expenditure can affect contractor pricing and development margins, although the statistical data do not establish how much of the wage increase has been passed through to construction contracts. The figures also cover construction activity broadly, including infrastructure works, rather than property development alone.
The construction sector’s performance contrasts with transportation and storage, where employment declined by 4% year-on-year, the largest reduction among the ten sectors monitored. Separate turnover figures published on the same day showed that transportation and storage revenues increased by 8.8% in September, the strongest annual growth recorded in the sector during 2026.
The divergence is relevant to Slovakia’s industrial and logistics property market because employment and business turnover provide different indicators of occupier conditions. Rising revenues do not necessarily require additional staff or warehouse accommodation, particularly where businesses are changing operating processes or making more intensive use of existing facilities. However, the figures do not establish whether logistics companies are expanding, consolidating or reducing their property requirements.
Manufacturing employment also declined, although the reduction was comparatively modest at 0.4% year-on-year. This followed a 0.2% decrease in industrial turnover during September, ending three consecutive months of growth. For industrial property owners and developers, the combination points to uneven manufacturing conditions rather than a clear indication of either expanding or contracting demand for production facilities.
Other sectors relevant to commercial property also reported workforce reductions. Employment in wholesale, retail trade and the sale and repair of motor vehicles declined by between 3.1% and 3.7%. These trends provide additional economic context for retail and distribution property markets, although employment changes alone cannot determine future leasing activity or space requirements.
By contrast, selected market services increased employment by 5%, while accommodation recorded growth of 4.6%. These sectors also experienced higher inflation-adjusted earnings, with real wage growth in accommodation exceeding 5%. The results suggest continued recruitment in parts of the service economy, potentially supporting business activity associated with commercial premises and hospitality operations.
Across the ten monitored sectors, nominal wages increased in every category during September, while real wages rose in nine. Construction recorded the strongest real increase at 8.5%, followed by accommodation and wholesale, where growth exceeded 5%. Information and communication was the only sector to report a decline in real earnings, at 1.4%.
The figures for the first nine months of 2026 reinforce the differences between construction and other parts of the economy. Employment in construction, accommodation and selected market services increased by at least 3% year-on-year, while wholesale recorded the largest cumulative reduction at 3%. Transportation and storage registered the strongest real wage growth over the nine-month period, at 2.9%, despite its September employment decline.
For Slovakia’s real estate market, the most immediate implication concerns construction expenditure. Sustained wage growth could add pressure to development budgets, particularly for projects with limited flexibility to absorb higher costs. In the industrial and logistics sector, the contrasting movements in turnover and employment suggest that occupier performance should be assessed alongside actual leasing activity, warehouse utilisation and investment plans before drawing conclusions about demand for additional space.
The latest figures therefore present two different challenges for property market participants: managing construction labour expenditure and interpreting changing business conditions among industrial and logistics occupiers. Both will be relevant to development decisions, although the statistical release does not directly measure property rents, construction contract prices or warehouse take-up.
The Statistical Office noted that the results are preliminary and based on monthly surveys. Employment figures include employees and entrepreneurs, while wage statistics exclude business income.