Thursday, 12 November 2026
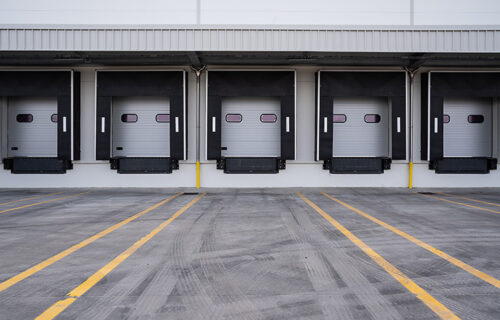
Poland’s industrial and logistics property market recorded its highest leasing volume for the first nine months of any year in 2026, with gross take-up reaching 5.3 million sq m, approximately 20% above the corresponding period of 2025. According to Colliers, stronger demand for warehouse accommodation has reduced vacancy across the country, while developers are increasing construction activity in response to occupier requirements.
Modern warehouse and industrial stock reached nearly 37.8 million sq m at the end of September 2026. Approximately 1.5 million sq m of new accommodation was completed during the first three quarters, broadly matching the volume delivered a year earlier. However, the combination of new leasing commitments and the occupation of existing buildings meant that additional supply did not result in higher overall availability.
Net take-up, which excludes lease renewals and renegotiations, increased by more than 50% year-on-year to 3.4 million sq m. This indicates that the rise in leasing activity was driven substantially by new agreements and occupier expansions rather than the extension of existing contracts.
Logistics operators and e-commerce businesses were among the principal sources of demand. Colliers estimates that companies from China accounted for approximately 20% of net take-up during the first nine months of 2026, highlighting their contribution to warehouse leasing activity in Poland.
Antoni Szwech, Senior Business Analyst in the Market Insights department at Colliers, commented: “The scale of growth in net demand shows that we are not simply dealing with the renewal of existing leases, but with a genuine increase in demand for warehouse space. The record results reflect both the expansion of e-commerce and the continued development of distribution networks. This is one of the strongest indications of the Polish logistics market’s healthy condition.”
The increase in occupier demand has been accompanied by a reduction in available space. Poland’s warehouse vacancy rate fell from 8.2% a year earlier to 5.5% at the end of the third quarter, its lowest level since the end of 2022. The decline has been particularly noticeable in the segment of larger warehouse units, where tenants have fewer immediately available options.
According to Colliers, units exceeding 20,000 sq m represented approximately 40% of the total available warehouse offer around a year ago. By the end of September 2026, their share had fallen to approximately 15%. The reduction means that companies requiring substantial areas for distribution or manufacturing operations may increasingly need to consider buildings under development or facilities designed for their specific requirements.
Łukasz Pańczyk, Director in the Logistics and Industrial Department at Colliers, explained: “Companies looking for large warehouse spaces have significantly fewer options available today than they did a year ago. Increasingly, the most suitable solution is a project developed for a specific tenant or securing space at an early stage of a planned investment. For occupiers, strategic planning of leasing processes will become increasingly important in the coming quarters, affecting space availability, location choices and the commercial and legal terms that can be negotiated.”
Construction activity has also increased. Approximately 1.7 million sq m of warehouse accommodation was under development at the end of the third quarter, representing a 9% increase compared with the same period of 2025. Around 62% of the space being built had already been secured through leasing agreements, indicating that developers continue to rely heavily on confirmed occupier demand before proceeding with projects.
The Silesian region recorded the highest construction activity, with more than 640,000 sq m under development, its largest pipeline since 2022. More than 70% of this space had already been committed to tenants, leaving a relatively limited proportion available for new occupiers.
Although the national development pipeline has expanded, speculative construction remains below 40% of the total volume under development. This suggests that developers are maintaining a selective approach to projects without pre-arranged tenants, despite the improvement in leasing demand. Colliers reports that some developers are considering increasing speculative activity in established logistics locations during the coming quarters.
The changing balance between supply and demand could also influence rental levels. Following a period of relative stability, Colliers expects moderate upward pressure on warehouse rents, particularly for larger units where availability has declined most significantly.
Smaller warehouse premises face a different market environment, with a wider selection of available accommodation limiting the immediate potential for rental increases. The differences between unit sizes and locations are therefore expected to become increasingly important in determining leasing conditions.
The latest figures indicate that Poland’s warehouse market is experiencing stronger occupier activity alongside a more constrained supply of large, immediately available properties. Although the construction pipeline is expanding, the high proportion of space already leased suggests that new development may provide only limited relief in the short term for companies seeking substantial warehouse accommodation.