Tuesday, 10 November 2026
Inflation across Gulf economies remains relatively contained compared with the wider Middle East and North Africa, although geopolitical disruptions and higher energy costs are creating uneven price pressures across the region.
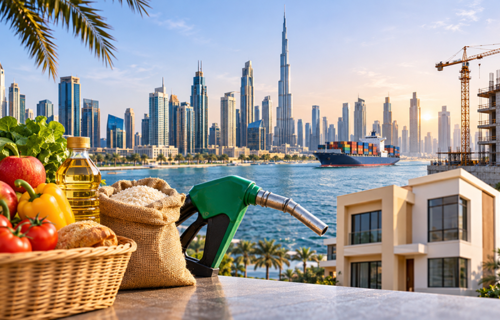
Inflation across the Gulf Cooperation Council (GCC) is expected to average 2.7% in 2026 before easing to 2.4% in 2027, according to Kamco Invest’s November 2026 GCC Inflation Update. The report highlights growing pressure from food, transport and housing costs, particularly as regional geopolitical tensions and disruptions to shipping routes affect supply chains and energy markets.
Despite these challenges, inflation across the six GCC economies remains considerably lower than in the wider Middle East and North Africa (MENA) region, where average inflation is projected to increase from 12.8% in 2025 to 14.9% in 2026. Kamco Invest attributes the Gulf’s relative price stability partly to energy subsidies, administered prices, currency pegs and fiscal policies.
The United Arab Emirates recorded the highest reported inflation rate among GCC economies, with Dubai’s consumer price index increasing by 5.0% year-on-year in September 2026. Although this represented a moderation from 5.5% in August, transport costs increased by 14.7%, reflecting higher fuel prices and airfares. Food and beverage prices rose by 8.1%, while housing, water, electricity, gas and domestic fuel costs increased by 6.2%, supported by rising residential rents across the emirate.
The housing component is particularly relevant for the UAE property market, where rental increases continue to contribute to consumer price pressures. While the report does not provide detailed transaction or rental market data, the increase in housing-related costs indicates the continued importance of residential accommodation in Dubai’s inflation profile.
Saudi Arabia recorded the lowest inflation rate among the GCC economies covered, at 1.9% year-on-year in September 2026. Housing-related costs remained an important contributor, with prices in the housing, water, electricity, gas and other fuels category rising by 3.6%. Actual housing rents increased by 3.5%, while food and beverage prices rose by 1.4% and transport costs by 2.3%.
The figures suggest that residential rental inflation continues to influence Saudi Arabia’s consumer price index, even as overall inflation remains relatively moderate.
Qatar experienced stronger price pressures, with annual inflation reaching 4.1% in August 2026, compared with 4.0% in July and 2.2% in June. Food and beverage prices increased by 11.0% year-on-year, representing the largest reported increase among the country’s major inflation categories. Kamco Invest links the acceleration partly to disruptions affecting liquefied natural gas exports and shipping through the Strait of Hormuz.
In Bahrain, annual inflation reached 3.2% in September 2026. Transport costs increased by 11.6%, while food and non-alcoholic beverages rose by 8.0%. Housing, water and electricity prices, however, declined by 1.3% year-on-year, illustrating the different inflation patterns across the region.
Oman also recorded inflation of 3.2% in September, driven by an 8.0% increase in food and non-alcoholic beverage prices and a 4.7% rise in transport costs. Restaurant prices increased by 3.6%, while furnishing and household equipment costs rose by 3.3%.
Kuwait’s latest reported inflation reading stood at 2.2% in July 2026. Food and beverage prices increased by 6.1%, while transport costs rose by 5.5%. Housing services recorded a comparatively modest increase of 0.2%, suggesting significantly less inflationary pressure in this category than in several neighbouring markets.
Beyond domestic consumer prices, Kamco Invest identifies disruptions to global energy and food supply chains as important influences on the regional inflation outlook. The report notes that restrictions affecting shipping through the Strait of Hormuz have reduced LNG deliveries from GCC producers, while higher transportation and fuel costs have contributed to price increases across several economies.
Global food prices have also increased. According to figures cited from the Food and Agriculture Organization, the FAO Food Price Index reached 136.0 points in September 2026, representing a 5.8% year-on-year increase. Cereal prices rose by 17.2%, with wheat and maize prices affected by supply constraints, shipping bottlenecks and adverse weather conditions.
Monetary policy has added another dimension to the economic outlook. The report states that the US Federal Reserve increased its benchmark interest rate by 25 basis points in September 2026, prompting corresponding increases by several GCC central banks. Saudi Arabia and Oman raised their repo rates to 4.5%, while Qatar increased its repo rate to 4.35%. Bahrain lifted its overnight deposit rate to 4.5%, and the UAE increased its base rate to 3.9%. Kuwait maintained its existing rates.
For property developers and investors, the combination of higher borrowing costs, rising construction-related expenses and continued rental inflation presents a mixed operating environment. Higher financing costs may influence investment decisions and development feasibility, while residential rental increases in markets such as Dubai and Saudi Arabia could support landlord income but place additional pressure on household affordability.
Looking ahead, Kamco Invest cites IMF projections indicating that GCC inflation will moderate to 2.4% in 2027 and return towards 2.0% from 2028. The outlook assumes lower commodity prices, continued exchange-rate stability and disciplined fiscal policies.
The report nevertheless underlines the importance of geopolitical developments and international supply chains in determining the pace of inflation across Gulf economies. Although the region remains comparatively resilient, differences in housing, transport and food costs are likely to remain significant considerations for consumers, businesses and real estate investors.