Wednesday, 18 November 2026
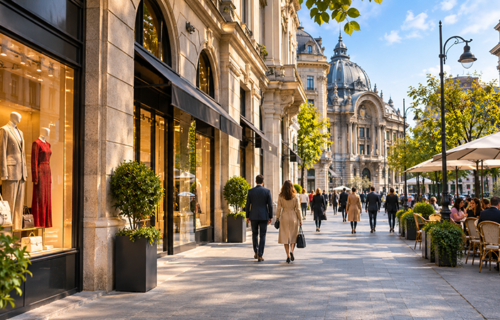
Prime retail rents on Bucharest’s Calea Victoriei increased by 29% over the past year, the strongest annual rise among the European locations examined in Cushman & Wakefield’s Main Streets Across the World 2026 report. The increase lifted the Romanian capital three positions to 35th place in the global ranking of the most expensive retail destinations, although rents remain considerably below those recorded in Prague, Budapest and the leading Western European shopping streets.
According to the consultancy, the headline rent for the most sought-after retail premises on Calea Victoriei reached €90 per sqm per month in 2026, compared with €70 a year earlier. The increase was the second-largest among the 50 markets represented in the global ranking, behind New York’s Upper Fifth Avenue. Bucharest now shares 35th position with Belgrade and Mexico City, reflecting similar rental levels in the locations used for the comparison.
The figures represent prime headline rents for selected retail premises rather than average rents across Bucharest’s entire shopping market. They also describe the asking or benchmark rental level associated with the most sought-after locations and should not be interpreted as evidence that every retailer on Calea Victoriei experienced a 29% increase in its occupancy costs.
Cushman & Wakefield attributes the increase partly to improvements in the surrounding public spaces and a rise in visitor numbers, including international tourists. These changes have coincided with demand from retailers seeking premises in central Bucharest, where the supply of suitable ground-floor accommodation is limited. The report does not provide transaction-level leasing evidence or detailed vacancy figures for the street, making it difficult to determine how much of the increase reflects newly agreed rents rather than changes in market benchmarks.
Dana Radoveneanu, Head of Retail Agency at Cushman & Wakefield Echinox, said the street had attracted greater interest from international retailers and Romanian businesses seeking central locations. She pointed to the limited availability of suitable premises as an important factor influencing rental levels. The consultancy’s observations suggest that demand for established city-centre retail locations is becoming more selective, particularly where retailers place importance on pedestrian activity, tourism and proximity to other commercial uses.
Despite the substantial annual increase, Bucharest remains less expensive than several established Central European retail markets. Prime rents in Prague reached €235 per sqm per month, approximately 2.6 times the level recorded on Calea Victoriei. Budapest followed at €180, while Warsaw stood at €94, only slightly above Bucharest. Belgrade recorded the same €90 monthly level as the Romanian capital.
Elsewhere in the region, the report identified rents of €70 per sqm per month in Zagreb, €63 in Sofia and €60 in Ljubljana. Bratislava recorded €45, followed by Vilnius at €39, Riga and Tallinn at €35 each, and Skopje at €28. These differences illustrate the considerable variation in retail property costs across Central and Eastern Europe, although direct comparisons are influenced by the individual streets selected, local purchasing power and the characteristics of available premises.
At the global level, New York’s Upper Fifth Avenue returned to first place after a 35% annual increase in prime rents to €2,083 per sqm per month. The location moved ahead of London’s New Bond Street, where rents remained unchanged at €1,720, and Milan’s Via Montenapoleone, which recorded €1,667. Both European streets had experienced substantial increases in earlier reporting periods but showed no further growth in the latest assessment.
Hong Kong’s Tsim Sha Tsui ranked fourth globally at €1,085 per sqm per month, following a 6% decline, while the Avenue des Champs-Élysées in Paris completed the top five at €1,043, unchanged from the previous year. Tokyo’s Ginza ranked sixth at €917, followed by Zurich’s Bahnhofstrasse at €795, Sydney’s Pitt Street Mall at €697, Seoul’s Myeongdong at €571 and Vienna’s Kohlmarkt at €450.
The international comparison highlights the scale of the difference between Bucharest and the world’s most expensive retail locations. Prime rents on Upper Fifth Avenue were more than 23 times those recorded on Calea Victoriei, while New Bond Street commanded approximately 19 times the Bucharest level. These differences reflect variations in international retailer demand, visitor spending, property availability and the commercial position of individual shopping districts.
The 2026 report examined prime retail rents across 147 urban shopping locations worldwide, with its global ranking based on the most expensive destination in each of 50 markets. Across all monitored locations, rental growth averaged 3.0% year on year in local currency terms, compared with 4.3% in the previous edition. The figures indicate a moderation in overall rental growth despite substantial increases in selected cities.
Nearly half of the locations surveyed, approximately 49%, recorded higher rents, while 32% remained unchanged and 19% experienced declines. In Europe, average rental growth was 2.9%, with increases recorded in 42% of the 57 locations monitored. Bucharest’s 29% rise therefore stands considerably above the regional average and contrasts with the more limited changes observed across much of the European market.
The different growth rates also demonstrate why changes in global rankings require careful interpretation. A city may improve its position because rents have increased locally, because competing destinations have recorded slower growth or because of exchange-rate movements affecting euro-denominated comparisons. The report’s annual growth figures are calculated in local currencies, while the international rental table presents values in euros.
For Bucharest’s retail property market, the increase on Calea Victoriei points to stronger competition for a limited number of centrally located premises. However, the effect on retailers will depend on individual lease terms, sales performance and operating expenses. Higher rents can improve the income prospects of property owners, but they may also restrict the range of businesses able to afford accommodation in the most expensive sections of the street.
The findings also raise questions about how rental growth will develop if the availability of suitable premises remains constrained. Established buildings in central locations cannot necessarily accommodate the space requirements of larger international retailers, while alterations to historic properties and existing commercial premises may involve planning and construction limitations. The report does not establish whether the current pace of rental growth is sustainable.
Calea Victoriei’s movement to 35th place reflects a substantial change in its reported prime rental benchmark during 2026. Nevertheless, Bucharest remains a comparatively affordable market within the European high-street hierarchy, particularly when measured against Prague and Budapest. Its future position will depend on retailer demand, visitor spending, the supply of suitable premises and whether the sharp increase in rents is supported by continued leasing activity.