Friday, 6 November 2026
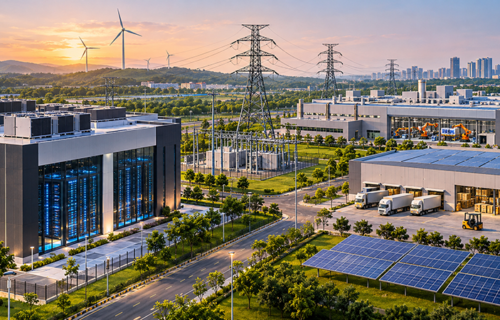
India’s expanding data centre and manufacturing sectors are placing greater demands on electricity infrastructure, with access to reliable power becoming an increasingly important consideration for commercial and industrial property development. While land availability, transport connections and proximity to major markets remain central to investment decisions, the capacity of local electricity networks is playing a larger role in determining where new facilities can be developed and how quickly they can become operational.
The shift is particularly evident in data centres, advanced manufacturing plants and specialised logistics facilities, where electricity requirements are considerably higher than those of conventional warehouses or commercial buildings. For developers and investors, the availability of suitable land must increasingly be assessed alongside the cost, reliability and timing of electricity connections.
India’s data centre industry illustrates the scale of this change. Industry estimates indicate that operational capacity reached approximately 1.5 gigawatts in 2025, compared with estimates ranging from 375 to 520 megawatts in 2020. Forecasts suggest that capacity could increase to between 4.5 and 6.5 gigawatts by 2030, supported by demand for cloud computing, artificial intelligence, financial technology and digital services.
This expansion is creating additional requirements for electricity distribution networks and supporting infrastructure. Data centres operate continuously and depend on stable electricity supplies to maintain their computing and cooling systems. Electricity is also one of their largest operating expenses, with industry estimates suggesting that energy can account for approximately 60–70% of operating costs in some facilities.
As a result, the availability of sufficient electricity capacity can influence development decisions before construction begins. Large data centre projects may require dedicated substations, additional transformers, backup systems and the ability to increase power consumption as facilities expand. Where the existing network cannot accommodate these requirements, developers may face additional investment costs or longer delivery schedules.
Mumbai remains one of India’s principal data centre markets, accounting for approximately one-quarter of the country’s facilities. Its established telecommunications networks, financial services industry and concentration of corporate occupiers have supported investment in digital infrastructure. However, the development of larger campuses is also encouraging activity across the wider metropolitan region, including Navi Mumbai, Thane and surrounding locations.
These areas can offer larger development sites and opportunities to accommodate additional technical infrastructure. Electricity availability is one consideration alongside land costs, fibre connectivity and the potential for future expansion. The movement towards peripheral locations therefore reflects a combination of property and infrastructure requirements rather than evidence of a general relocation caused by electricity shortages.
Similar considerations are becoming increasingly relevant to India’s manufacturing sector. Semiconductor production, electronics assembly, pharmaceutical facilities and electric vehicle battery manufacturing require dependable electricity supplies to maintain production processes and protect sensitive equipment. Interruptions or fluctuations in supply can result in production losses, equipment disruption and additional operating expenses.
India’s Electronics Manufacturing Clusters 2.0 programme reflects the importance of coordinating industrial investment with infrastructure development. By December 2025, the government had approved 11 electronics manufacturing cluster projects and two common facility centre projects covering approximately 4,400 acres across 10 states.
The programme is intended to support manufacturing investment through planned industrial infrastructure and shared facilities. However, approved projects are at different stages of development, and the availability of land does not necessarily mean that electricity connections and supporting utilities are ready for immediate industrial occupation.
For manufacturers evaluating new locations, this distinction can influence investment schedules. A development may offer suitable land, transport access and government incentives but still require substantial work to provide the electricity capacity needed for production. Delays in completing these connections can affect factory construction, equipment installation and the commencement of operations.
Electricity infrastructure is also becoming an important consideration for India’s industrial corridor developments. Projects such as the Visakhapatnam–Chennai Industrial Corridor are intended to encourage manufacturing investment through improved transport connections and industrial infrastructure. Their development will also require coordination with electricity providers to accommodate additional demand from factories and supporting facilities.
The challenge is not limited to the amount of electricity generated nationally. Local transmission and distribution capacity determines whether individual industrial locations can obtain the power they require. Even where sufficient generation is available, additional substations, network connections or distribution upgrades may be necessary before large industrial projects can operate.
India’s logistics property sector is experiencing similar changes, although electricity requirements vary considerably between occupiers. According to CBRE, industrial and logistics leasing across eight major Indian markets reached approximately 27.1 million square feet during the first half of 2025, representing a 63% increase compared with the corresponding period in 2024.
Third-party logistics operators accounted for approximately 32% of leasing activity, followed by e-commerce companies at 25% and engineering and manufacturing occupiers at 19%. The figures reflect continued expansion in distribution networks and industrial operations, although the increase in leasing cannot be attributed directly to electricity demand.
Nevertheless, the growing use of warehouse automation, refrigeration and electric vehicle charging is changing the technical requirements of certain logistics properties. Automated distribution centres require electricity for handling equipment and inventory systems, while cold-storage facilities depend on continuous power to maintain controlled temperatures.
These requirements can create significant differences between otherwise similar industrial buildings. A conventional storage warehouse may operate with relatively limited electricity consumption, whereas an automated or temperature-controlled facility may require considerably greater capacity and more extensive backup arrangements.
For developers, anticipating these requirements during the planning stage can reduce the need for expensive alterations when a property is leased. Industrial buildings with sufficient electricity capacity may also be better suited to occupiers seeking to introduce automation or expand their operations.
The increasing use of renewable electricity adds another consideration to industrial property investment. Companies operating data centres and manufacturing facilities are examining renewable energy procurement as part of their efforts to manage electricity costs and environmental commitments.
However, access to renewable electricity does not remove the need for reliable grid infrastructure. Solar and wind generation fluctuate, while many industrial operations require continuous supply. Businesses must therefore consider how renewable electricity arrangements can be combined with dependable network connections, storage or other supporting systems.
Electricity tariffs, transmission charges and state-level regulations can also influence the financial attractiveness of different locations. For energy-intensive occupiers, differences in electricity costs may affect long-term operating expenses and investment decisions.
These developments have implications for industrial land values and property investment strategies. Sites with confirmed electricity availability and sufficient capacity for future expansion may offer advantages over locations where substantial infrastructure upgrades are required.
However, the extent to which these advantages translate into higher rents or land prices remains dependent on local market conditions, occupier requirements and the availability of comparable properties. There is insufficient evidence to conclude that electricity-ready industrial sites consistently command a measurable premium across India.
The more immediate consideration for investors is the effect on development costs and project delivery. Additional electricity infrastructure can increase capital expenditure, while uncertainty over connection schedules may delay the completion or occupation of a facility.
As India’s digital economy and manufacturing base continue to expand, electricity infrastructure is likely to become a more prominent element of industrial property planning. The requirements of data centres, advanced factories and specialised logistics facilities are placing greater emphasis on coordination between developers, occupiers, electricity suppliers and public authorities.
For India’s commercial real estate market, the availability of land and transport infrastructure will remain important, but the ability to secure dependable electricity within a predictable timeframe could increasingly influence where major industrial investments are located. Developers able to align property construction with the delivery of essential power infrastructure may be better positioned to attract occupiers and manage the financial risks associated with large-scale projects.
Source: © CIJ.World India Research & Analysis Team