Sunday, 15 November 2026
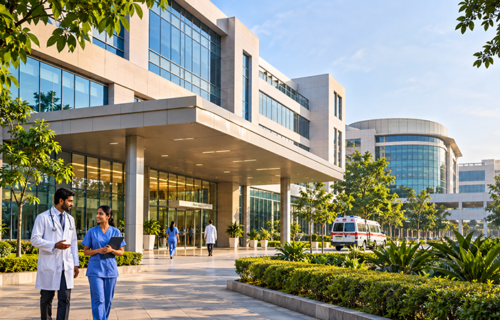
India’s healthcare sector is becoming an increasingly important area of activity for property developers and investors as hospital operators expand their networks, demand for specialist treatment increases and the country seeks to improve access to medical services. Beyond conventional hospitals, development opportunities are emerging in diagnostic centres, outpatient facilities, medical education institutions and larger healthcare complexes that combine several services within a single location.
The expansion reflects both demographic and economic changes. India’s large population, rising household incomes, increasing demand for private medical treatment and greater awareness of healthcare services are contributing to the need for additional facilities. However, the scale of investment required also highlights the challenges of developing medical infrastructure in a market where access to healthcare remains uneven between major cities and smaller urban centres.
According to research published by Rubix Data Sciences, India’s healthcare services market was valued at approximately US$638 billion in FY2025 and could reach US$1.52 trillion by FY2030. The projection covers the wider healthcare services industry rather than property investment specifically and depends on continued strong growth. Nevertheless, it illustrates the scale of the sector supporting demand for hospitals and related buildings.
A more direct indication of the potential property requirement comes from CBRE, which estimated in October 2026 that India had approximately 2.1 billion sq ft of healthcare real estate in 2025. Its research suggested that a further 2.6 billion sq ft could be required by 2035 if the country were to increase hospital-bed availability towards international averages. The estimate represents a long-term assessment of infrastructure needs rather than a confirmed development pipeline.
India currently has approximately 1.6 hospital beds per 1,000 residents, according to CBRE, compared with a global benchmark of around 3.3. Addressing this difference would require substantial expenditure on land, construction, medical infrastructure and staffing. The geographical distribution of new facilities will also be important, as healthcare provision remains concentrated in larger metropolitan areas while many smaller cities and regional communities face more limited access to specialist treatment.
Private hospital groups are already planning significant expansion. Credit rating agency ICRA estimated in February 2026 that 18 major hospital operators could add more than 34,000 beds between FY2026 and FY2030, involving investment of approximately ₹40,000 crore. The planned expenditure includes new hospital developments, extensions to existing facilities and acquisitions, meaning that not all of the investment will translate directly into additional construction.
Major healthcare operators, including Apollo Hospitals, Max Healthcare, Global Health and Aster DM Healthcare, have been pursuing expansion strategies involving additional hospital capacity and specialised services. Their investment programmes create opportunities for construction companies, property owners and developers capable of delivering buildings with the technical infrastructure required for modern medical operations.
Unlike conventional commercial buildings, hospitals require extensive electrical and mechanical systems, specialised ventilation, reliable backup power, medical gas infrastructure and carefully designed circulation areas. Diagnostic equipment, operating theatres and intensive-care facilities can also impose substantial structural and servicing requirements. These characteristics make healthcare development more complex than standard office or retail construction and increase the importance of working closely with hospital operators during the design process.
The property market is also seeing examples of hospital operators securing facilities through acquisitions and long-term leases. In Mumbai, Manipal Health Enterprises completed a transaction involving hospital property and associated development rights in Andheri, with the wider acquisition valued at approximately ₹908 crore. The investment illustrates the importance of securing suitable urban sites where existing medical facilities and opportunities for expansion can be difficult to replicate.
In Bengaluru, Manipal Health Enterprises was also reported to have entered into a hospital property lease extending for nearly 30 years, with a total contractual value of approximately ₹816 crore. Such arrangements demonstrate how healthcare operators can secure long-term occupation of specialised buildings without necessarily purchasing the underlying property. For landlords, these agreements can provide extended rental commitments, although the financial strength of the operator and the cost of maintaining specialised premises remain important considerations.
Another area of development is the combination of hospitals with medical education, research and supporting accommodation. Larger healthcare sites can include teaching facilities, laboratories, rehabilitation services, pharmacies and residential space for medical professionals or patients’ relatives. Bringing these activities together may improve operational coordination and create demand for several property types within the same development.
India already has examples of institutions combining medical education and clinical services, including Adesh Medical College near Ambala in Haryana. However, such projects vary considerably in scale and organisation, and integrated medical campuses should be regarded as one development approach rather than an established model across the entire healthcare market.
Public investment is also contributing to the expansion of healthcare infrastructure. The Pradhan Mantri Ayushman Bharat Health Infrastructure Mission was approved with an allocation of ₹64,180 crore for FY2021–22 to FY2025–26. The programme supports improvements to public medical facilities, including critical-care services and laboratory infrastructure. Although this expenditure is primarily directed towards public healthcare, it also contributes to construction activity and the wider development of medical infrastructure.
Specialist healthcare facilities represent another area of potential growth. Services covering cancer treatment, fertility, ophthalmology, kidney care, orthopaedics and rehabilitation often require buildings designed around particular medical procedures. Diagnostic laboratories and outpatient treatment centres can operate in smaller premises than full-service hospitals, allowing providers to establish facilities in locations where developing a large hospital may not be commercially justified.
These formats can also offer different property investment characteristics. A diagnostic centre may require relatively limited space but significant electrical capacity and technical installations, while a specialist hospital can involve substantial upfront expenditure on clinical infrastructure. The suitability of individual properties therefore depends on the operator’s business model, patient volumes, regulatory requirements and the potential for future adaptation.
Private equity investment has helped finance the expansion of healthcare operators, although investment in medical businesses should not be confused with direct ownership of healthcare property. Industry research has recorded substantial transactions involving hospital chains and specialist providers, but these investments frequently cover acquisitions, equipment, technology and operating businesses rather than buildings alone.
International patients provide an additional source of demand for some Indian hospitals, particularly those offering complex procedures and specialist treatment. Official tourism statistics recorded approximately 507,000 foreign arrivals for medical purposes in 2025. This was below the approximately 644,000 recorded in 2024, indicating that international patient demand can fluctuate despite India’s established position as a destination for medical treatment.
For real estate investors, the appeal of healthcare facilities lies partly in their specialised use and the possibility of long-term relationships with established operators. However, these characteristics do not eliminate investment risks. Hospital profitability depends on patient volumes, treatment costs, insurance arrangements, staffing availability and regulatory conditions. Buildings designed for highly specialised medical activities may also be expensive to convert if an operator leaves.
Development costs present another challenge. Suitable urban land can be expensive, while hospital construction requires substantial expenditure on technical systems and compliance. Projects in smaller cities may benefit from lower land costs, but investors must assess local healthcare demand, the availability of qualified medical professionals and the financial capacity of prospective patients.
The distinction between healthcare demand and commercially viable property development will become increasingly important as operators consider expansion beyond established metropolitan markets. Areas with limited medical provision may have considerable social need without necessarily supporting the operating costs of a large private hospital. In such locations, smaller treatment centres, diagnostic facilities or partnerships with public institutions may provide more practical development options.
India’s healthcare expansion is therefore creating a broader range of opportunities for the property industry, extending from hospital construction and refurbishment to specialist premises and long-term leasing arrangements. Research from CBRE and ICRA indicates that substantial additional infrastructure could be required over the coming decade, while recent property transactions demonstrate that investment activity is already taking place.
The pace of development will ultimately depend on financing, healthcare affordability, staffing and the ability of operators to sustain their services. For developers and institutional investors, the opportunity is significant, but successful projects will require a detailed understanding of medical operations as well as conventional real estate fundamentals.
Source: © CIJ.World India Research & Analysis Team